Nolo Missed the Islands. Its Wind and Water Didn’t.
Nolo never made landfall, but it pushed 88 mph gusts through West Maui and sent floodwater back through Kaʻū. If something changed at your home or business, it can be a real claim — even when the storm “missed.” Island Claims is Hawaiʻi’s licensed public adjusting firm. We work for property owners, never insurance companies.
Storm facts through Sept 29, 2026 HST from the Central Pacific Hurricane Center, NWS Honolulu, Hawaiian Electric, Hawaiʻi County Civil Defense and the Hawaiʻi National Guard. Full details and sources: Hurricane Nolo Property Damage & Claim Guide. Hero: Nolo on Sept 27 with West Maui and Kaʻū marked (NOAA GOES-West).
Update · Nolo is moving away
Late on Sept 29, Nolo had weakened to a tropical storm near French Frigate Shoals, far from the main islands, and every watch and warning for the main islands ended Sept 26. There is still no official count of damaged homes. What matters now is what changed at your property — document it before cleanup and repairs erase the evidence, then tell us what happened.
Central Pacific Hurricane Center advisory 39 · 11 p.m. HST Sept 29
Complimentary Nolo Property & Claim Review
Not sure whether Nolo damaged your property? Tell us what happened — our licensed Hawaiʻi team reviews every submission.
Mahalo! We Have Your Submission.
Our team will review what Nolo did to your property, and the licensed PA best suited to your loss will reach out to schedule a call and walk through your next steps.
ISLAND CLAIMS · WE’VE GOT YOU
NWS-listed gusts · West Maui · Sept 26–27
88mph · Olowalu
74mph · Ukumehame Gulch
66mph · Launiupoko
Point observations from NWS Honolulu (6:03 a.m. HST, Sept 27); NWS notes not all listed data are official. Actual wind at any property varies with terrain, elevation and exposure.
Why Nolo Claims Get Missed
Three Things Nolo Owners Get Wrong. We Help With All Three.
Nolo wasn’t a direct hit, so many owners assume there’s nothing to claim. Sometimes that’s true. Often it isn’t — and the evidence disappears with the cleanup.
1 · “The roof looks fine.”
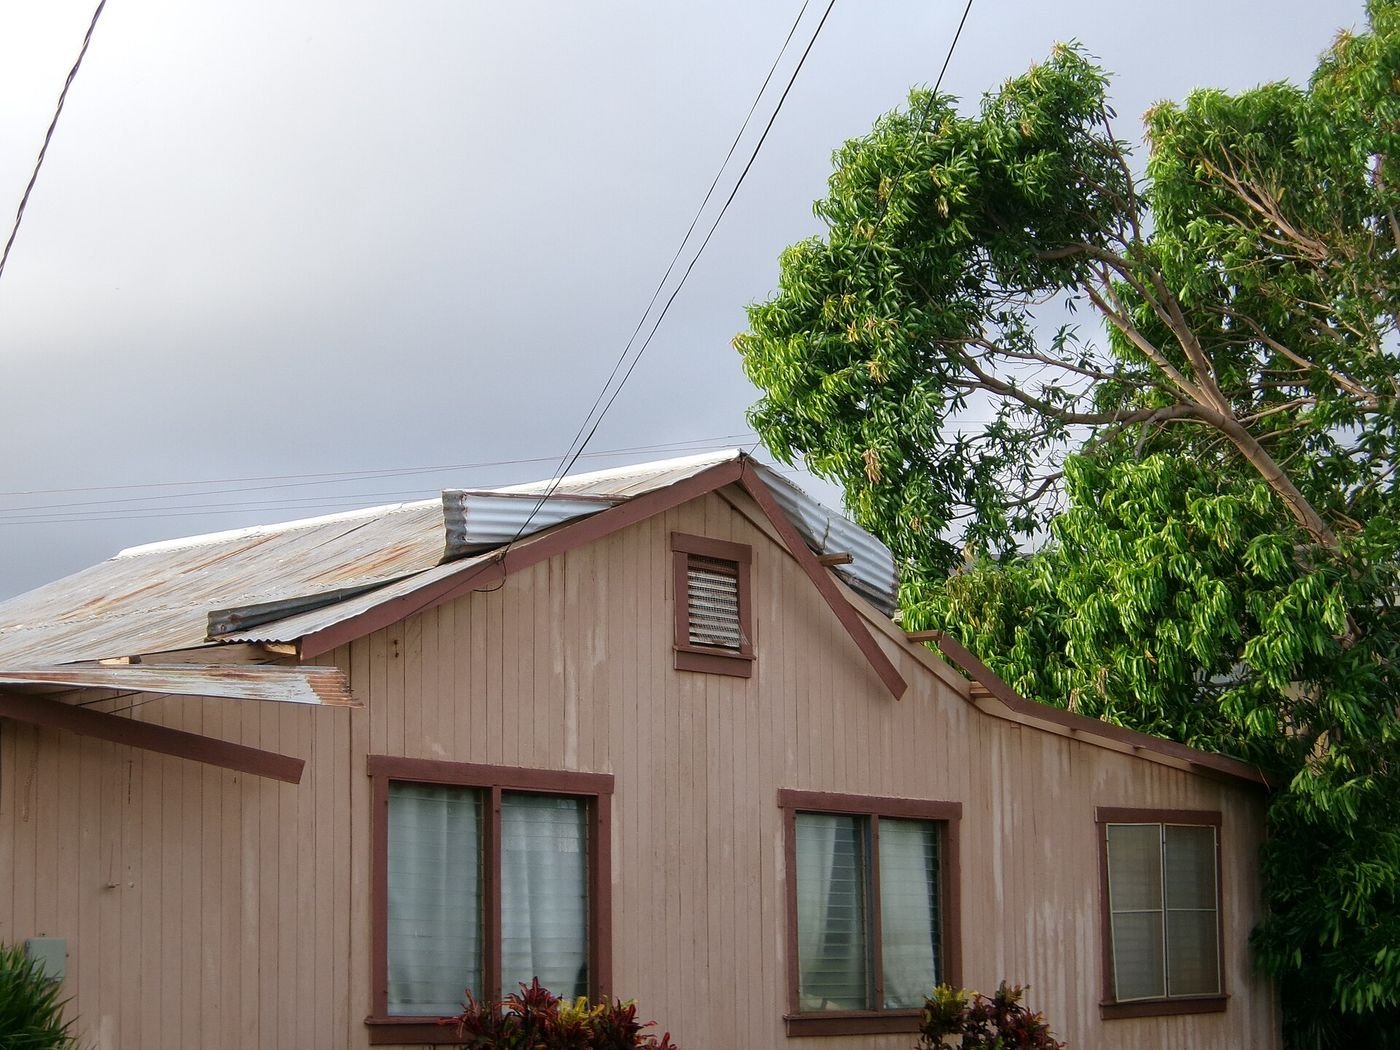
Wind uplift can break shingle seals, shift tile, unseat ridge caps and loosen flashing while everything still looks present from the street. Those openings leak weeks later, when it’s harder to tie them to the storm. Inspect now — from the ground, or with a qualified inspector or drone. Never climb a wet roof.
Waimea, Kauaʻi · Hurricane Lowell, Sept 2026 · A plantation-style home hit by Lowell’s winds · Kgcnew · CC BY-SA 4.0
2 · “It’s all Lala damage anyway.”
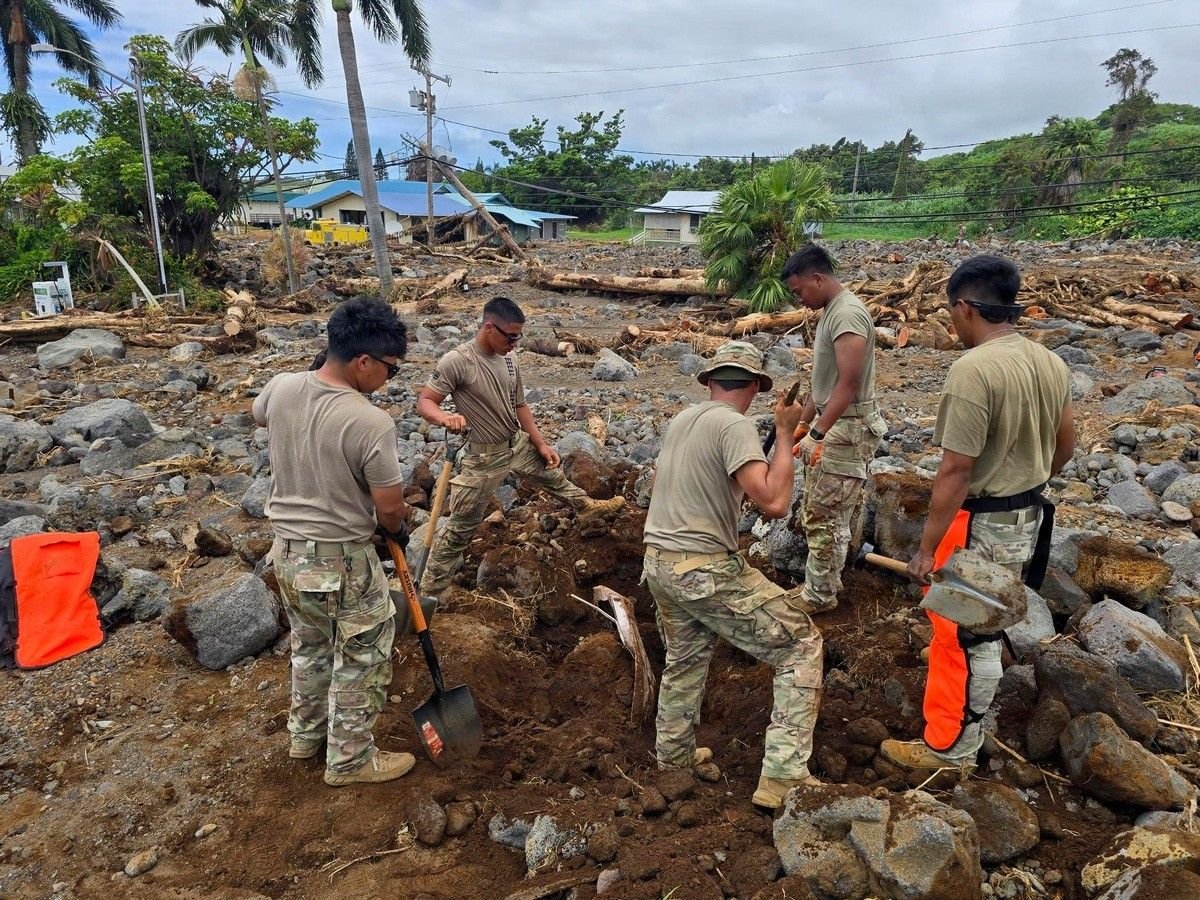
In Kaʻū, Nolo sent new water and mud through properties still recovering from Lala. Two storms means two dates of loss. Keep your Lala records and document what changed after Nolo — accurately. We never guess which storm did what; we investigate cause, date and mechanism.
Nāʻālehu, Kaʻū · Hurricane Lala, Aug–Sept 2026 · Clearing a debris flow between homes — the same town Nolo reflooded · U.S. Army National Guard · Public domain
3 · “Water damage is water damage.”
Surface flooding, rain through a wind-created opening, wind-driven rain and runoff can be treated very differently — and many Hawaiʻi owners have a homeowners, hurricane and flood policy. Where and how the water got in decides which policy may respond.
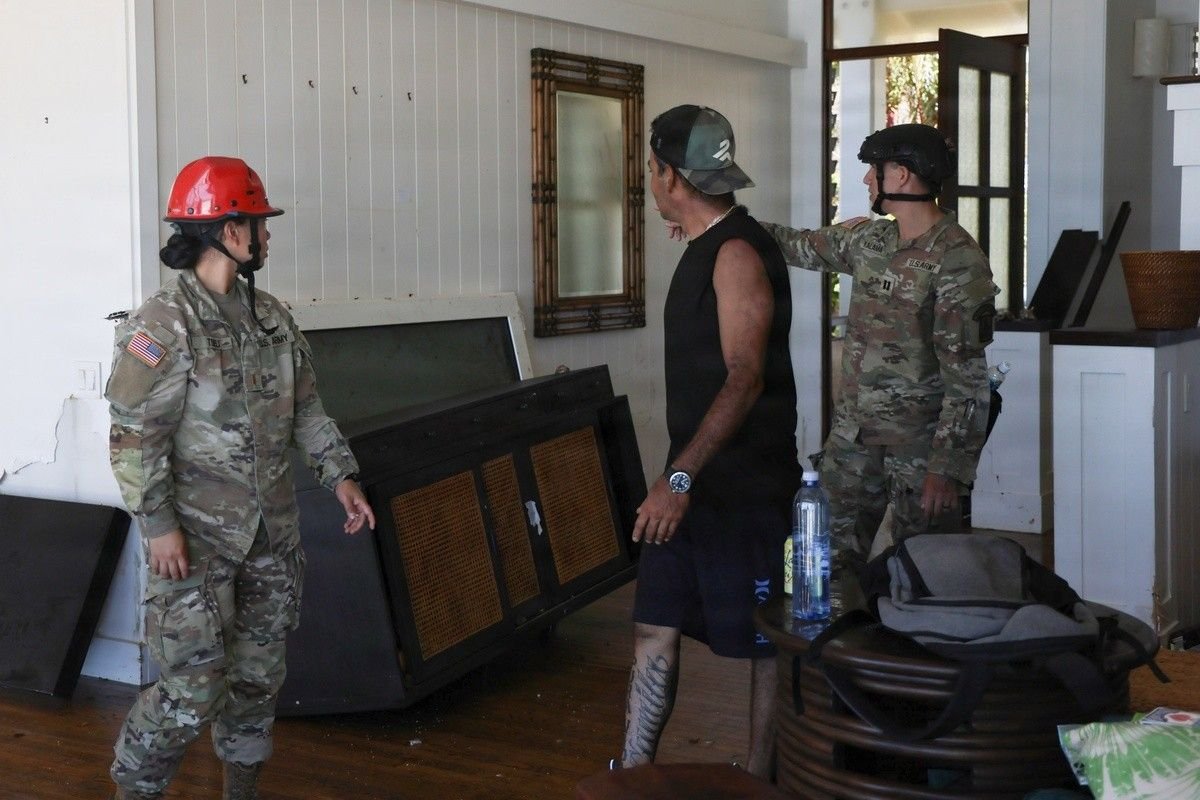
Poʻipū, Kauaʻi · Hurricane Lowell, Sept 2026 · A homeowner walks responders through the damage inside · U.S. Army National Guard · Public domain
What it costs$0 upfront, ever. Your review is Complimentary. If we take your claim, our fee is a percentage of the recovery — stated in writing before any work begins. No recovery, no fee. Hawaii Public Adjuster License #553921.
Before You Accept a Deductible
Does a Hurricane Deductible Apply to Nolo Damage?
Many Hawaiʻi policies swap your regular deductible for a much larger, percentage-based hurricane deductible — often tied to whether the National Weather Service issued a hurricane watch or warning. Here is exactly what was issued for Nolo:
Hawaiʻi County · Hurricane watch11 a.m. Sept 23 to 11 a.m. Sept 26, plus a tropical storm warning from Sept 24. A hurricane deductible may be argued here — the exact trigger wording decides.
Maui County · Tropical storm watch onlyFrom Sept 24. Never a hurricane watch or warning. West Maui’s damaging winds came under high wind warnings.
Oʻahu & Kauaʻi · No watches or warningsNolo’s effects here were wind, rain and surf without any tropical watch or warning.
Trigger wording varies — some policies refer to your island or county, others to any part of the state — and the Insurance Division (Memo 2026-7A) has told insurers that the policy language controls and each claim must be judged on its own facts. If your insurer applied a hurricane deductible to a Maui, Oʻahu or Kauaʻi loss, or you’re not sure which deductible applies on Hawaiʻi Island, have it reviewed before you accept. Learn more in our Hawaiʻi hurricane deductible guide and claim worksheets.
88 mphgust · Olowalu~12,370Maui customers out Sept 27100+ acresOlowalu brush fire
NWS-listed gusts of 88 mph at Olowalu, 74 at Ukumehame Gulch and 66 at Launiupoko. Lahaina to Kapalua lost power early Sept 27, along with parts of Haʻikū and Upcountry; Hawaiian Electric says major Nolo outages were restored by Sept 29.
Check roofing, ridge caps, flashing, solar, lanai covers, fences and trees
Businesses: spoilage, outage and access losses along Honoapiʻilani Hwy
Strongest flood signal
Kaʻū
19people rescued by the GuardHwy 11flooded Pāhala–WaiʻōhinuSept 23–26hurricane watch
Runoff overflowed a gulch at Highway 11 in Waiʻōhinu, sending mud and debris into homes and buildings. The National Guard ran high-water rescues, shelters opened in Nāʻālehu, Pāhala and Ocean View, and water use is still limited in Nāʻālehu, Waiʻōhinu, Discovery Harbour and South Point.
Much of the heavier damage here is from Lala — document what changed after Nolo
Check water and mud lines, crawlspaces, flooring, drywall and contents
Wind & rain exposure
Kohala & East Hawaiʻi
67 mphgust · Kohala Mtn Rd14+ in.rain at the highest elevations
Kohala Mountain Road closed for high winds; a landslide and downed tree hit ʻŌʻōkala, and 4,000+ Hawaiʻi Island customers lost power Sept 27.
Check roofs, solar and outbuildings on exposed slopes
Watch for slope, drainage and retaining-wall issues after heavy rain
No watches issued
Kauaʻi & Niʻihau
0watches or warningsSurfsouth & west shores
Nolo passed far to the southwest without a watch or warning for Kauaʻi or Niʻihau. Surf and passing rain were the main effects, and no Nolo damage reports have surfaced so far.
Still recovering from Lowell? New Nolo damage would be a separate date of loss
Photograph anything that changed
High-wind exposure
Oʻahu, Molokaʻi & Lānaʻi
80 mphridge-top gust · Waimano~5,000Oʻahu customers out at peak
Ridge-top gusts reached 80 mph on Oʻahu, where outages peaked near 5,000 customers on Sept 27 (Kahuku and Hauʻula among the hardest hit). Molokaʻi and Lānaʻi were under high wind warnings; no concentrated building damage has been reported.
If something changed at your property, document it the same way
Before · Sept 20Nolo · Sept 26
Drag to compare. The same view of Hawaiʻi a week apart — clear skies, then Nolo’s bands over the islands the night Kaʻū flooded. NOAA GOES-West (public domain).
Real Hawaiʻi Homes & Businesses
What Storm Damage Looks Like Here
Roofs peeled back, interiors soaked, a whole row of homes opened up at once, a snapped palm on a downtown office — big losses and “small” ones. Every photo is a real Hawaiʻi property, labelled by place, storm and year. Tap any photo to enlarge.
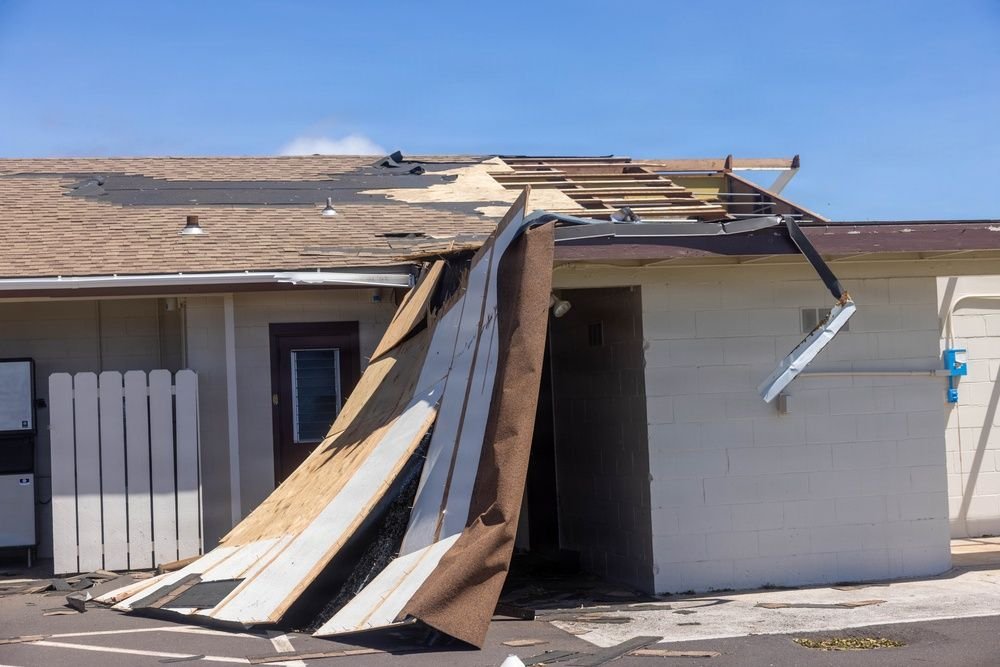
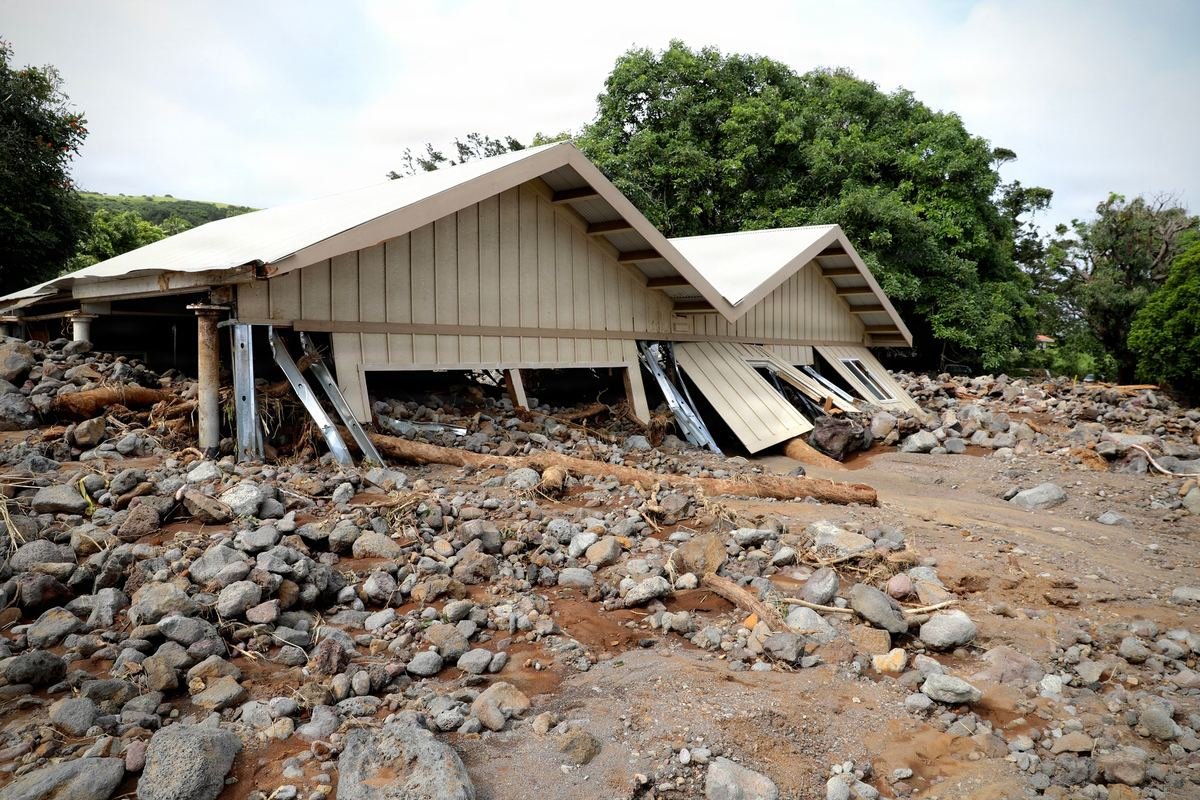
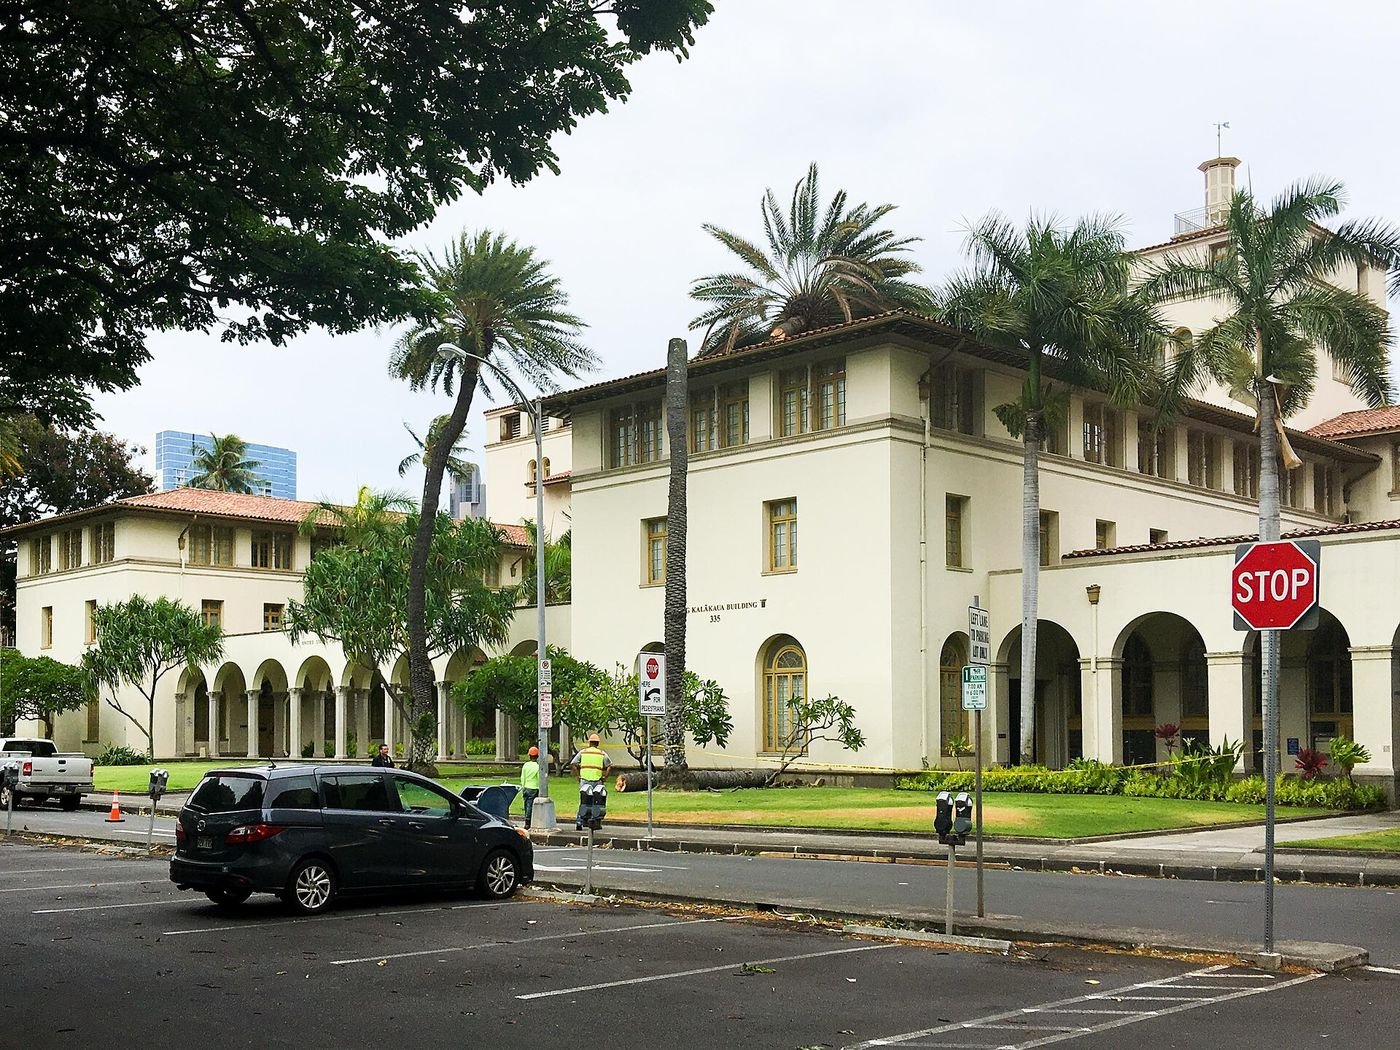
Waimea, Kauaʻi · Hurricane Lowell, Sept 2026A plantation-style home hit by Lowell’s windsKgcnew · CC BY-SA 4.0Wind & tree damagePoʻipū, Kauaʻi · Hurricane Lowell, Sept 2026A homeowner walks responders through the damage insideU.S. Army National Guard / Staff Sgt. Nate Ragragola · Public domainInterior damageKekaha, Kauaʻi · Hurricane Lowell, Sept 2026Roofing and fascia peeled off an office buildingU.S. Navy / Jonell Kaohelauliʻi · Public domainCommercial roofNāʻālehu, Kaʻū · Hurricane Lala, Aug–Sept 2026Clearing a debris flow between homes — the same town Nolo refloodedU.S. Army National Guard / Staff Sgt. Benadetti · Public domainFlood & debrisKaʻū · Hurricane Lala, Aug 2026Home pushed off its foundation by a debris flowHawaiʻi Army National Guard · Public domainFlood & debrisHonolulu · Hurricane Lane, 2018A snapped palm on a commercial building — “minor” that still needs a lookDaniel Ramirez · CC BY 2.0Minor damage
How It Works
Three Steps. No Upfront Cost.
Tell us what happened
Two minutes on the form above — add photos if you have them. Not sure anything is wrong? Say so; that’s what the review is for.
We inspect & read your policy
A licensed Hawaiʻi adjuster looks at the property and the wording — hurricane deductible trigger, flood vs. wind-driven rain, business income — and tells you honestly whether there’s a claim.
We document, present & negotiate
If there is, we build the scope priced for Hawaiʻi, handle the insurer and push for the full settlement. You pay nothing unless you recover.
Not sure Nolo did anything?
You don’t need a missing roof to justify a closer look. If your property was in Nolo’s wind or water, let a licensed local adjuster check it before repairs change the evidence.
For the main Hawaiian Islands, yes. Every watch and warning for the main islands ended on September 26. Late on September 29, Nolo was a weakening tropical storm near French Frigate Shoals in the Northwestern Hawaiian Islands, far from any community. Nolo never made landfall on a main island; its damage came from outer rain bands, terrain-enhanced winds and surf. Now is the time to document — before cleanup and repairs erase the evidence.
It depends on your policy’s trigger wording and your island. A hurricane watch covered Hawaiʻi County from September 23 to 26. Maui County only had a tropical storm watch, and Oʻahu and Kauaʻi had no watches or warnings at all. Many Hawaiʻi hurricane deductibles are tied to a hurricane watch or warning, but the exact wording differs by policy, and the Insurance Division (Memo 2026-7A) has reminded insurers that the policy language controls, claim by claim. If a hurricane deductible was applied to your claim, have the wording checked before you accept it.
Yes. Wind uplift can break shingle seals, crease tabs, loosen fasteners, shift tile, unseat ridge caps and loosen flashing while the roof still looks complete from the street. NWS-listed gusts reached 88 mph at an Olowalu station, 74 mph at Ukumehame Gulch and 66 mph at Launiupoko. Please do not climb on the roof — a qualified inspection or drone documentation is the safe way to check.
Lala (August), Lowell (early September) and Nolo (September 23–27) are separate events with separate dates of loss. Keep your earlier photos, estimates, invoices and proof of repairs, and document what changed after Nolo. We investigate cause, date, mechanism, policy, prior condition and repairs so each occurrence is presented accurately — never guessed.
It depends on where the water came from and how it got in. Surface flooding, rain through a wind-created opening, wind-driven rain without an obvious opening, and runoff or drain backup can all be treated differently, and many Hawaiʻi owners have more than one policy (homeowners, hurricane, flood). Coverage depends on the exact wording and endorsements in force — exactly what a Complimentary review looks at.
Not for individual homeowners so far. The federal emergency declaration approved September 25 covers emergency protective measures by government agencies; it does not include Individual Assistance. Your insurance policy is the main path to recovering property losses. Still report damage to your county — Hawaiʻi County has residential and commercial damage-report forms — because those reports shape any future aid.
Not the ones issued so far. The Insurance Division’s September memo asking insurers to allow extra time to pay premiums (Memo 2026-8A) covers Lala, Lowell and the March Kona Low — not Nolo. Keep your policies paid, and if you need more time, ask your insurer in writing.
No. The Insurance Commissioner’s September 25 declaration lets insurers bring in out-of-state independent adjusters for Lala, Lowell and Nolo, but it specifically excludes nonresident public adjusters. Anyone representing you should hold a Hawaiʻi public adjuster license. Island Claims is Hawaiʻi-licensed (#553921) and Maui-based.
Possibly, but not automatically. Some commercial policies include business income, extra expense, civil authority, ingress/egress, utility service interruption or spoilage coverage, each with its own triggers, waiting periods and limits. An outage or closure alone does not establish coverage. Keep outage records, closure notices, sales records and receipts, and have the wording reviewed.
Policies require prompt notice of a loss, and specific deadlines vary by policy — for proof of loss, supplements and disputes. Hidden damage can also surface weeks later. Report promptly, document thoroughly, and get your policy’s deadlines identified early. We do that in every Complimentary review.
These programs cost nothing and are separate from your insurance claim — use them. None of them replaces what your policy may owe you for your property.
Every photo on this page shows a real Hawaiʻi property after a Hawaiʻi storm, labelled with the place, storm and year. Creative Commons images are used unmodified except for resizing.