Hurricane Lala Recovery · Major Disaster Declaration Requested Sept 9

Lala Damaged Your Property.
Don’t Let the Insurance Company Decide What It Was Worth.

Hurricane Lala damaged 267 homes across the state — 217 of them on Hawaii Island, where 27 were destroyed — and left more than $67 million in validated public damage, with Hawaii County’s estimate approaching $100 million. Five weeks in, the first inspections and first checks have arrived, and the claims will be won or lost on documentation, classification, and negotiation. Island Claims is Hawaii’s licensed public adjusting firm. We represent property owners only. Never insurance companies.

Start Your Complimentary Lala Claim Review
Federal Status
Emergency Aug 25 · Major Pending
EM-3652 covers Hawaii, Maui & Honolulu counties; Individual Assistance requested Sept 9, awaiting approval
Homes Damaged
267 Statewide
217 in Hawaii County (27 destroyed, 60 major); $67M+ validated public damage, ~$100M county estimate; Kaʻū hardest hit
Power Lost
~200,000 Customers
Extended outages — food spoilage & business losses count too
The Claim Window
Five Weeks In
First checks are arriving; supplements and reopened claims are normal. Hidden damage surfaces for months. Deadlines run either way.

Storm facts from official reporting as of September 22, 2026 (state damage validation, Hawaii County, HI-EMA). Emergency info: Hawaii Emergency Management — Lala updates · disasterassistance.gov

Kaʻū flooded again during Hurricane Nolo (Sept 26–27). Nolo is a separate event with its own date of loss — if something changed at your property, see our Hurricane Nolo claim help page.

Complimentary Lala Claim Review

Our licensed Hawaii team reviews every submission and responds with your assessment

Tap to upload or drag and drop

Damage photos · Policy · Claim docs · PDF, JPG, PNG · 20MB max each

No upfront cost. We only get paid when you receive your settlement.
Your information is confidential — see our Privacy Policy. Mahalo.Hawaii Public Adjuster License #553921

Mahalo! We Have Your Submission.

Our team will review your Lala claim, and the licensed PA best suited to your loss will reach out to schedule a call and walk through your next steps.

ISLAND CLAIMS · WE’VE GOT YOU
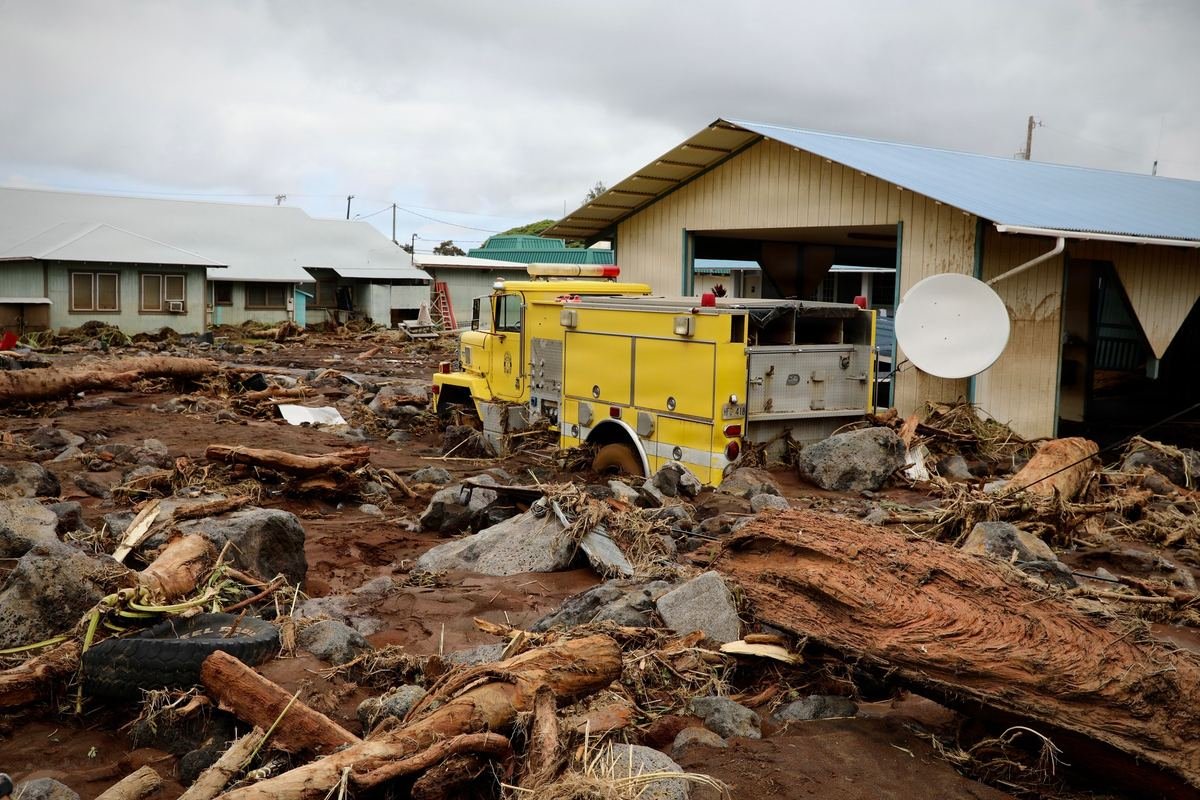
A fire truck buried in mud and debris between damaged buildings after Hurricane Lala on Hawaii Island
Debris flows buried entire properties when Lala stalled over the islands. Hawaii National Guard response in the Ka‘u District, Hawaii Island, August 2026. Photo: Hawaii Army National Guard, 117th Mobile Public Affairs Detachment (public domain).
Why Lala Claims Get Underpaid

Three Fights Are Here. We Fight All Three.

After an island-wide event, carriers fly in catastrophe adjusters who have never seen single-wall construction or priced materials that arrive by barge. Then the classification games begin.

1 · Wind vs. Flood vs. Earth Movement

Wind damage is generally covered. Rising water is “flood.” Landslides get labeled “earth movement.” When Lala delivered all three at once, how your loss gets classified can decide the entire claim — and the first classification is not the final word. Evidence decides this fight, and early documentation wins it.

2 · The Losses Nobody Claims

~200,000 customers lost power. Refrigerators and freezers full of food, spoiled restaurant inventory, business income lost to closures and civil-authority orders — these are real, claimable losses that most owners never file. Photograph before you dispose. Every documented dollar counts.

3 · The Fast, Low First Offer

Catastrophe-scale claims mean rushed inspections and mainland pricing databases. First offers after events like Lala routinely miss hidden moisture, code upgrades, and real Hawaii rebuild costs. Estimates are negotiable. Supplements are normal. Do not accept a number that doesn’t rebuild your property.

Hurricane deductible applied?

A hurricane watch or warning alone doesn’t decide your deductible.

On August 26, Hawaiʻi’s Insurance Commissioner told insurers to evaluate each Lala claim on its own facts and the policy’s actual wording — and not to treat a hurricane watch or warning as the same thing as the storm’s classification unless the policy says so. Coverage and deductible decisions must be clearly explained (Commissioner’s Memorandum 2026-7A).

Lala brought a hurricane warning to the Big Island, but Maui County and the other islands were under tropical storm warnings. If a percentage hurricane deductible was applied to your Lala claim, it deserves a close look.

Get a Complimentary Deductible Review
What it costs$0 upfront, ever. Your review and inspection are Complimentary. If we take your claim, our fee is a percentage of the recovery — stated in writing before any work begins. No recovery, no fee. Hawaii Public Adjuster License #553921.
Lala Claim Questions

Answers Before You Sign Anything

Not automatically. After Lala, Hawaiʻi’s Insurance Commissioner reminded insurers that a hurricane watch or warning is not interchangeable with the storm’s classification unless the policy says so, that each claim must be judged on its own facts and policy wording, and that deductible decisions must be clearly explained (Memorandum 2026-7A). Maui County and most islands were under tropical storm — not hurricane — warnings. Ask your insurer in writing which provision and which warning it relied on, and let us review it.
Policies require prompt notice of a loss, and specific deadlines vary by policy — for proof of loss, for supplemental claims, and for recovering withheld depreciation. Hidden storm damage also surfaces for months. The safest move: report promptly, document thoroughly, and get your policy’s specific deadlines identified early. We do that in every Complimentary review.
This is the central battleground of storm claims. Wind damage and rain entering through wind-created openings are generally covered by hurricane or homeowners policies; rising water is generally flood (separate NFIP coverage); and “earth movement” language is where many claims get wrongly classified. The first determination is not the final word — get the file professionally reviewed before you accept it.
Not yet. The August 25 emergency declaration (EM-3652) covers Hawaii County, Maui County and Honolulu, but it primarily authorizes public emergency measures. The Governor requested a Major Disaster Declaration with FEMA Individual Assistance on September 9; as of September 22 it is still pending. If approved, registration opens at disasterassistance.gov with its own deadline. Your insurance policy remains the primary path for your property losses, and accepting FEMA help does not settle anything with your insurer — FEMA also will not duplicate what insurance pays, so getting the claim right comes first.
Usually not. Most first checks after catastrophes are partial payments, and supplemental claims are a normal part of the process — but read the wording before you endorse anything that says “full and final.” Our insurance check guide explains exactly what to look for, or send us the check letter and we’ll review it with your claim.
Official Lala Recovery Help

State & County Programs You Can Use Right Now

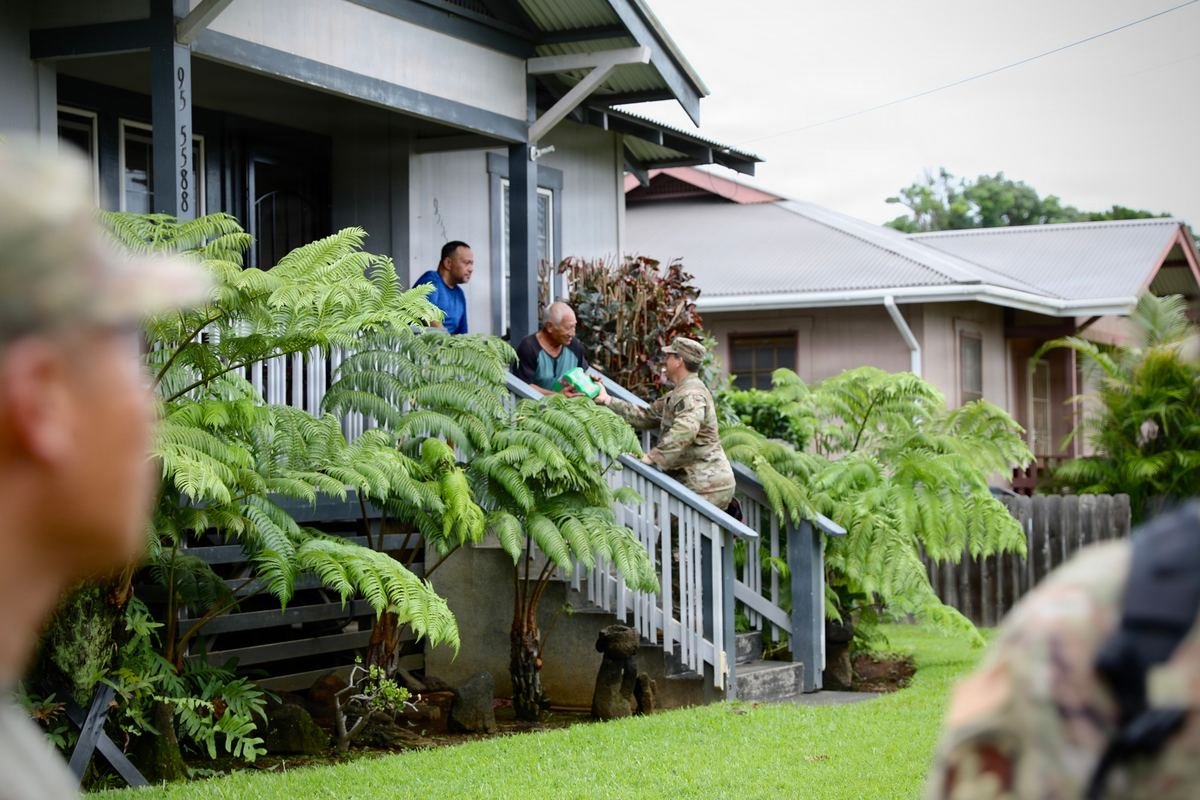
A Hawaii National Guard member checking on residents at their home after Hurricane Lala
Guard members going door to door on welfare checks after Lala. Real help is out there — use all of it. Hawaii National Guard response in the Ka‘u District, Hawaii Island, August 2026. Photo: Hawaii Army National Guard, 117th Mobile Public Affairs Detachment (public domain).
Insurance claim questions & complaintsHawaii Insurance Division — state regulator, free help for policyholders
Temporary housing assistanceFor residents displaced by Tropical Storms Lala & Moke · daily 9am–6pm
Food replacement (SNAP)Reimbursement for food lost to outages over 4 hours or flooding — current SNAP recipients
State tax reliefPenalty & interest waivers for impacted taxpayers, August 20 – October 20, 2026
All official Lala updates & damage reportingHawaii Emergency Management Agency — county damage report forms, road & utility status
Emotional support, 24/7Hawaii CARES · free, confidential · disaster distress line 1-800-985-5990

These programs are free and separate from your insurance claim — use them. None of them replaces the money your policy owes you for your property, which is the claim we help you fight for.

Helpful Resources

Whether You Hire Us or Not