Commercial & Condo Insurance Claimsfor Owners, Boards & Property Managers
When a storm, fire or water loss hits a building you own or manage, the insurance company shows up with adjusters, engineers and accountants. Island Claims gives you your own side of the table: a licensed Hawaiʻi public adjuster who leads your file, with estimators, engineers, CPAs and other specialists brought in as the loss needs. We document the whole loss, price it for the islands and handle the insurer, so owners, boards and managers can keep the property running.
Island Claims is a public adjusting firm, not a law firm. We work alongside your broker, managing agent, contractors and, when a dispute calls for it, your attorney.
Three roles, one goal: the building restored and the claim paid right.
Commercial claims involve more people than a home claim. Choose the one that sounds like you.
A trusted resource for your owners and boards
When a building you manage is damaged, we carry the claim, deal with the insurance company and keep your owners and board informed. You stay their go-to.
Working with managers →Owners, boards & businessesAn adjuster who works for you, not the insurer
Hotels, condo associations, retail, office, industrial and mixed-use. We document the whole loss, price it for Hawaiʻi and handle the claim through settlement.
Start a review →Contractors & tradesYou fix the building. We handle the claim.
Roofers, general contractors, restoration and mitigation crews: send the owner to us from the job site, and we work to get the full scope documented and approved.
Partner with us →Complimentary Commercial Claim Review
Open claim, low offer, or denial? Tell us about the property and where the claim stands — a licensed Hawaiʻi public adjuster reviews every submission, including the insurer’s estimate and letters if you have them.
Mahalo! We Have Your Submission.
We’ll review your property and claim, then reach out to schedule a call with your licensed public adjuster and walk through your next steps.
ISLAND CLAIMS · WE’VE GOT YOU
Eight Warning Signs a Large Claim Is Going Sideways
None of these requires a denial letter. Each one can cost six or seven figures on a hotel, condo tower, farm or commercial building — and each one is easier to fix while the claim is still open.
- The estimate is far below your contractor’s numbersMainland pricing, missing line items, or no allowance for barge freight and island labor.
- Partial payments, then silenceAn advance arrives, then months of requests for more documents with no decision.
- A hurricane deductible was appliedOn a large building a percentage deductible can erase most of the payment — check the trigger wording.
- Their engineer blames wear and tearConflicting expert reports that turn storm damage into “pre-existing” or “maintenance.”
- Business income is being cut shortThe period of restoration ends before you can actually reopen, or ongoing expenses are left out.
- Code upgrades were left outPermits require upgrades the estimate doesn’t include — often a separate coverage.
- Smoke, water or mold called “cosmetic”Hidden damage in HVAC, walls and ceilings treated as a cleaning job.
- Deadlines are getting closeProof of loss, appraisal and suit-limitation dates are approaching and the claim isn’t resolved.
The insurer has its adjuster, engineers and accountants. So should you.
On a large loss the insurance company assembles a team: a field adjuster, a desk adjuster, building consultants, sometimes a forensic accountant. Their reports become the claim file. We build yours — with our own inspection, a line-item estimate priced for Hawaiʻi, and documentation organized so every reviewer can approve it.
Four Parts of Every Large Claim. We Work All Four.
1 · The building — and what code requires now
Repairs to an older building often trigger today’s code: roofing, electrical, energy and accessibility upgrades. Ordinance or law coverage can pay for those upgrades, and the cost can count once the code is enforced — for example, when a permit is conditioned — not only after the work is paid for. We identify code items before the estimate is agreed.
2 · Business income & extra expense
Business income is measured over a period of restoration, and the start and end dates matter. We document sales history, continuing expenses, payroll, the dates payments arrive and every delay, so the claim reflects the time you were actually closed or slowed — plus the extra expense of staying open.
3 · Contents, equipment & inventory
Furniture in 200 hotel rooms, a commercial kitchen, pool pumps, farm equipment, retail stock. Large contents claims are won with organized inventories, models and serial numbers, and replacement pricing that includes shipping to the islands.
4 · Layered policies & deductibles
Master policy, hurricane policy, excess layers, flood, owners’ HO-6 policies and loss assessments. We map which policy responds to which damage, confirm the right deductible was applied, and keep the insurers from leaving you in the gap between them.
When a building you manage is damaged, we carry the claim.
Property managers sit between owners, boards, tenants, vendors and the insurance company, usually on top of a full workload. We take the claim work off your desk and keep everyone informed, so you can stay focused on the property and the people in it.
Owners notice who brought in help that worked. We want that to be you.
One organized file per building
Photos, estimates, invoices, insurer letters and deadlines in one place, kept per property and per claim.
Updates you can forward
Plain-English status updates written for owners, boards and ownership groups, so you aren't translating adjuster-speak.
The insurer goes through us
Document requests, inspections, re-inspections and follow-ups are handled in writing, with every date tracked.
Your vendors' work counted
Mitigation, tarping and emergency repair invoices are documented into the claim, so the people you called in can be paid.
Deductibles & assessments mapped
Master policy, hurricane deductible, owners' HO-6 policies and loss assessments, with options explained under your documents and HRS §514B-143.
Every island, one contact
Buildings on Maui, Oʻahu, Hawaiʻi Island and Kauaʻi handled with one point of contact for your whole portfolio.
- Introduce us
Send us the property and a contact for the owner or board. A short call is enough to get started.
- We meet the owner or board
The agreement is always with the policyholder, the owner or the association, never the manager. Our fee is explained in writing before anything is signed.
- You stay in the loop
With the owner’s OK, you’re copied on updates and inspection dates, so nothing about the property catches you off guard.
We don’t pay or accept referral fees, in either direction; that’s our own policy. Managers bring us in because it helps the owners they serve. Brokers and CPAs: see how we work with you. Island Claims is a public adjusting firm, not a law firm.
Commercial & Association Property Across Hawaiʻi
From a single storefront in Paʻia to a 300-unit condominium in Waikīkī, the work is the same: understand the policy, document the loss completely, and price it for Hawaiʻi.
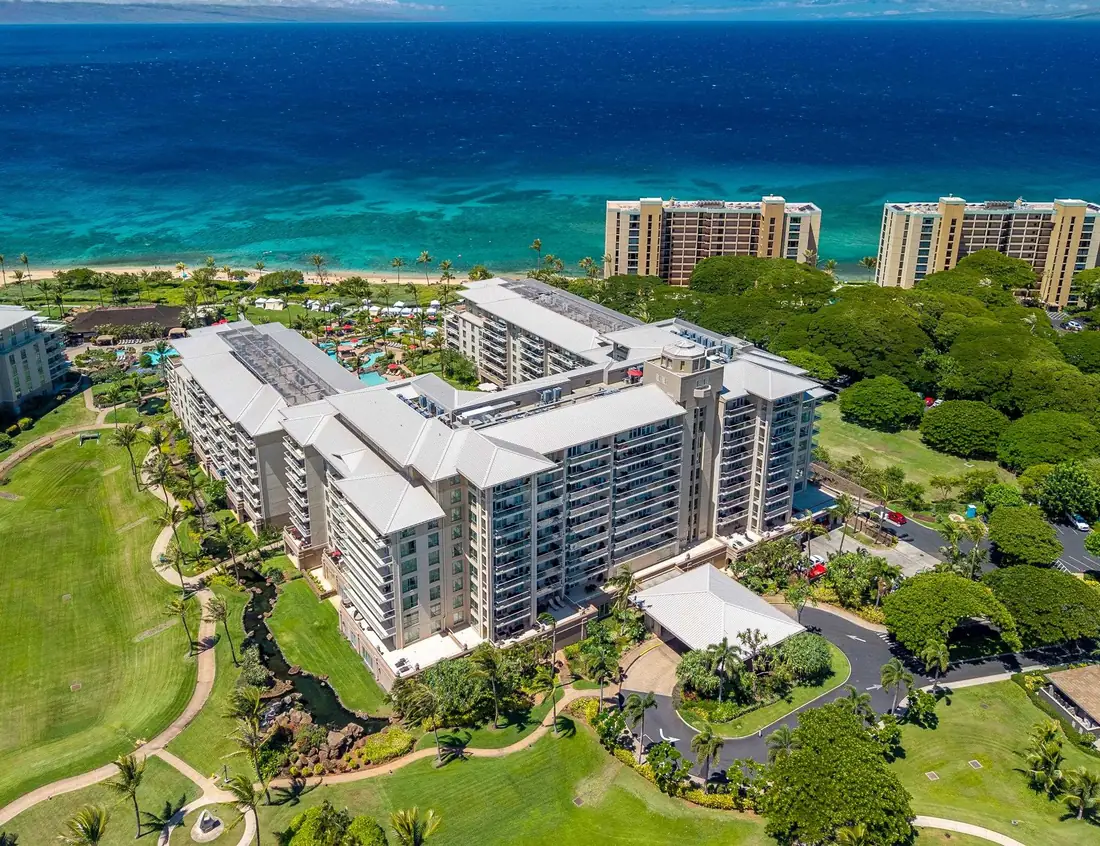
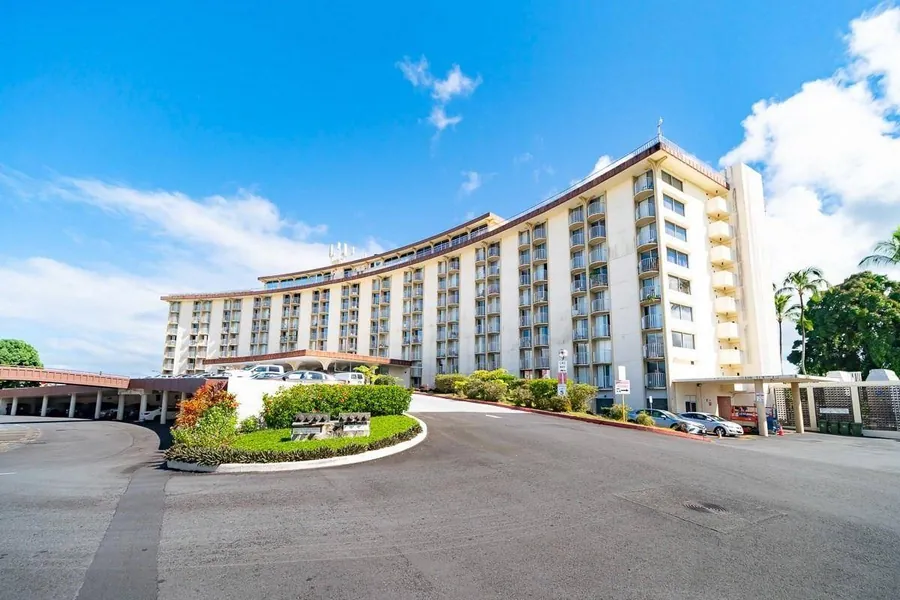
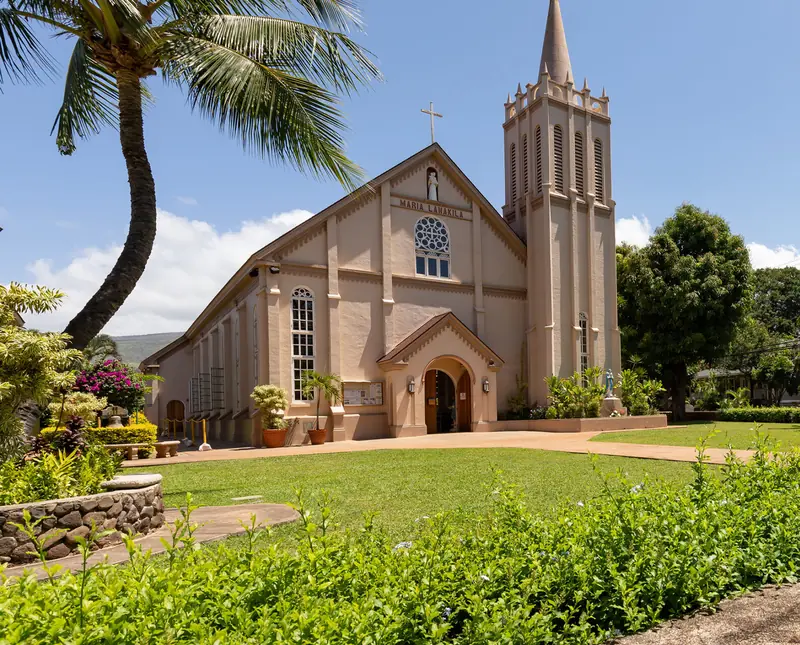
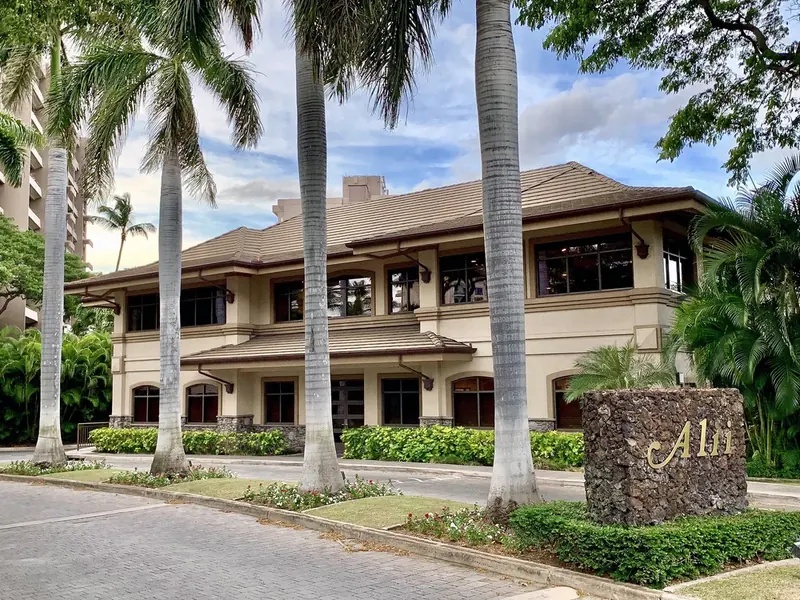
Photos show representative Hawaiʻi properties, not Island Claims clients.
Master policy claims, common elements, unit damage and owner assessments.
Rooms, amenities, contents and lost bookings during repairs.
Barns, greenhouses, equipment, fencing and ag structures.
Sanctuaries, halls, schools and community buildings.
Storefronts, kitchens, inventory, spoilage and closures.
Offices, warehouses, industrial and mixed-use properties.
Multi-unit rentals, tenant coordination and lost rents.
Classrooms, gyms, clinics and shared-use spaces.
From Coverage Map to Final Settlement
The same steps on every commercial and association file, in the same order. You can hold us to them.
We confirm who can sign for the owner or association, run a conflict check, make sure emergency protection is under way at every building, and request the complete certified policy and the insurer’s claim file in writing.
Every coverage, limit, deductible, condition and deadline, building by building, with the form number and page it comes from. Notice, proof of loss, appraisal and suit-limitation dates go on the calendar on day one.
One folder per building: elevations, roof measurements, unit-by-unit surveys, moisture maps and labeled photos. Engineers, roof consultants or code reviewers are brought in when the file needs them, and only after you approve the cost in writing.
A line-item estimate for each building, split by coverage: building, business property, ordinance or law, debris removal and more. Hawaiʻi pricing for freight, barging, permits and island labor, code items kept separate, the deductible math shown, and a coinsurance check against your statement of values.
One point of contact for the insurer, a written recap after every call, and a dated log of every request, response and payment, measured against the claim-handling standards in Hawaiʻi law (HRS §431:13-103) and your policy’s own deadlines. Undisputed amounts are requested by coverage as they’re agreed.
A one-page summary the managing agent can forward, plus a short decision memo whenever the board or owner has to decide something, such as a deductible allocation, appraisal or an offer.
Every figure is traced to its source and checked in a separate review before Joshua signs off. Nothing goes to the insurer without your approval, a sworn proof of loss is signed by your authorized officer, and no check marked “final” is accepted while more is owed.
We negotiate directly with the insurer. If the policy’s appraisal process fits a dispute over the amount, we help you invoke it. If a dispute needs an attorney, we help you bring one in early and work alongside them. Settlement is accepted only with your written approval, and a board resolution for an association.
Who works on your file
The licensed public adjuster leads, and specialists are added only as the loss calls for them. Shown here as roles, because the right firm depends on the building and the island.
Joshua Reeder, Lic. #11127106. Leads the file, deals with the insurer and signs off every submission.
Line-item estimates by building and coverage, priced for Hawaiʻi.
Cause-and-origin and roof condition reports when the insurer disputes the damage.
Code-upgrade lists for older buildings and ordinance or law coverage.
Business income and extra expense models built from your records.
Moisture maps and lab results for interior water damage.
Your counsel, brought in early when a dispute turns on the law, not the price.
Kept in the loop with your OK. We stay on the claim, not the placement.
What a board summary covers
A generic outline of the one-page update we send boards and owners as the claim moves. It is an example structure only: no real client, property or figures.
One or two sentences: the claim stage and anything that changed since the last update.
Inspections held, documents sent and received, and what the insurer said, with dates.
The next steps: who is doing what, and when.
Records, access dates or approvals, each with a due date.
Any decision needed, the options and what each one means, and the date it’s needed. Legal questions go to association counsel.
Proof of loss, debris-removal notice, replacement cost notice, appraisal and suit-limitation dates, and the insurer’s response deadlines.
Claimed, paid and disputed, by building and by coverage, once numbers exist. Every figure traced to an estimate line, invoice or insurer letter.
Written so any owner could read it, because association records can be open to owners. Distributed by the managing agent.
Managing agents: a printable board leave-behind is on our page for managers, brokers and CPAs.
Hawaiʻi claim worksheets
Loss Documentation Worksheet, ALE & Extra Expense Tracker, Hurricane Deductible Explainer and Proof-of-Loss Checklist — print-ready PDFs for owners, boards and managers.
The checks a careful board would make. Here are the answers.
Before an association or a business hands its claim to anyone, it should know who holds the license, how money moves and how its records are handled.
Licensed Hawaiʻi Public Adjuster #11127106
Joshua Reeder holds the license and leads every file. Verify it yourself on the Hawaiʻi Insurance Division’s license search (it runs on the NAIC lookup), or read how to check any adjuster’s license.
Bonded as Hawaiʻi law requires
Hawaiʻi requires a licensed public adjuster to keep a surety bond in force with the State (HRS §431:9-223). Your written agreement confirms it.
Insurance money goes to the policyholder
Insurer payments are made out to you or the association, with any mortgagee or loss payee, never to Island Claims alone. If we ever hold funds for a client, they go into a separate trust account and are paid out as Hawaiʻi law requires.
A written contract before any work
A Hawaiʻi Public Adjuster Contract states the fee, itemizes any expenses, and gives the policyholder three business days to cancel. Specialists are engaged only after you approve the cost in writing.
Your financial records stay on your claim
P&Ls, tax returns, rent rolls and board minutes are used for your claim and shared only with the insurer and the specialists you approve. See our Privacy Policy.
Policyholders only, no referral fees
We never work for insurers. Island Claims doesn’t pay or accept referral fees, in either direction. That’s our own policy. Island Claims is a public adjusting firm, not a law firm.
You fix the building. We handle the claim.
Roofers, general contractors, restoration and mitigation companies see the damage first. Hawaiʻi law keeps the repair and the claim separate: you never negotiate with the insurance company, and we don’t do construction. When we’re on the claim, the full scope gets documented and argued, so the job can be done right.
- 01You spot the damageRoof, water, wind or fire, on a job or an estimate visit.
- 02Refer in a minuteA short form from your phone, with the owner’s OK. The owner hears from us directly.
- 03We build and negotiate the claimYour estimate and photos become part of a full-scope claim priced for Hawaiʻi.
- 04Claim funded, work beginsThe property goes back to pre-loss condition.
Know Your Policy Before the Next Storm
Plain-language guides for owners, boards and property managers: what a commercial policy covers, the clauses that shrink claims, and what to do in the first 30 days.
Commercial Property Insurance in Hawaiʻi
The building, your business property, causes of loss forms, valuation and the small coverages with big deadlines.
Read the guide →
The Coinsurance Penalty
Underinsured by a little, underpaid by a lot. The formula, a worked example, and how to prevent or question it.
Read the guide →
Ordinance or Law Coverage for Hawaiʻi Commercial Buildings
Rebuilding to today’s code can cost more than the damage. Coverages A, B and C, and how to prove code costs.
Read the guide →
AOAO Master Policy Claims
What the statute requires, who pays the deductible, hurricane deductibles, and a step-by-step board checklist.
Read the guide →
After a Commercial Property Loss in Hawaiʻi
Day one through day thirty: protect, notify, document, and the deadlines to put on the calendar now.
Read the guide →
Business Income and Interruption Claims
Closed by storm damage, outages or road closures? How business income claims work and the records that prove them.
Read the guide →Answers for Owners, Boards & Managers
Whether You Hire Us or Not
Hawaiʻi Claim Worksheets
Document the loss, track extra expenses, check your hurricane deductible and assemble a proof of loss.
Hurricane Deductibles in Hawaii
Percentage deductibles, trigger language, and the coverage gray zones unique to Hawaii.
Depreciation, ACV & Replacement Cost
How withheld depreciation works — and how to recover it after repairs.
Claim Denied in Hawaii: Your Options
What a denial letter really says, and the steps that can turn it around.