Hurricane Lowell · Sept 7–8, 2026

Lowell Hit Kauaʻi Hard.
Don’t Let Your Claim Come Up Short.

880 damage reports, 18 homes destroyed and 100 with major damage on Kauaʻi — and three weeks later, first estimates, letters and checks are arriving. Before you accept a number, make sure it covers everything Lowell actually did: roof and interior water, wind-driven rain, fallen trees, surge and mud, outages and lost income. Island Claims is Hawaiʻi’s licensed public adjusting firm — we represent property owners only, never insurance companies.

Damage Reports
880
Resident damage reports on Kauaʻi as of Sept. 25: 18 homes destroyed, 100 with major damage (County of Kauaʻi). Businesses report separately
Peak Listed Gust
92 mph
Puʻu Lua, Kauaʻi · 87 Nāwiliwili · 85 Waimea · 84 Līhuʻe (NWS point observations; conditions vary by property)
Rain in 72 Hours
21.11 in
Kilohana, Kauaʻi · 18.63 in on Mt. Waiʻaleʻale (NWS). Flash flooding on the North Shore; most of the island lost power
Federal Aid
Pending
Major Disaster Declaration requested Sept. 9 for Kauaʻi & Maui counties — still pending Sept. 28. Your insurance claim doesn’t wait for FEMA

Storm facts from official reporting through Monday, September 28, 2026 HST (County of Kauaʻi, NWS Honolulu, KIUC, Office of the Governor, Hawaiʻi Insurance Division). Full details, sources and island-by-island checklists: Hurricane Lowell Claim & Recovery Guide. Photos show the kinds of damage Lowell owners are dealing with; the hero shows Kauaʻi homes after Hurricane Iniki (1992, FEMA). Captions name each photo’s storm and source.

Complimentary Lowell Property & Claim Review

Already filed, already paid, or not sure where to start? Tell us what Lowell did — our licensed Hawaiʻi team reviews every submission, including the insurer’s estimate if you have one.

Tap to upload or drag and drop

Damage photos · Policy · Claim docs · PDF, JPG, PNG · 20MB max each

No upfront cost. We only get paid when you receive your settlement.
Your information is confidential — see our Privacy Policy. Mahalo.Hawaii Public Adjuster License #553921

Mahalo! We Have Your Submission.

Our team will review what Lowell did to your property, and the licensed PA best suited to your loss will reach out to schedule a call and walk through your next steps.

ISLAND CLAIMS · WE’VE GOT YOU

NWS-listed gusts · Kauaʻi · Sept 7–8
92mph · Puʻu Lua
87mph · Nāwiliwili
85mph · Waimea

Point observations from the NWS Honolulu Hurricane Lowell summary (Sept. 9). Lowell passed about 90 miles west of Līhuʻe as a Category 2; actual wind at any property varies with terrain, elevation and exposure.

Why Lowell Claims Come Up Short

Three Places Lowell Claims Get Underpaid. We Help With All Three.

After a storm this size, insurers bring in adjusters from across the country and move fast. A quick first inspection is a starting point — not the final word on what your policy may owe.

1 · “The first estimate only counts what they saw.”

Wet insulation, moisture in walls and ceilings, lifted shingles and loosened flashing, damaged solar mounts, electrical and lanai damage are easy to miss in a short visit. Missed items mean a missed payment. Supplements are how they get added back — with photos, moisture readings and a line-by-line estimate.
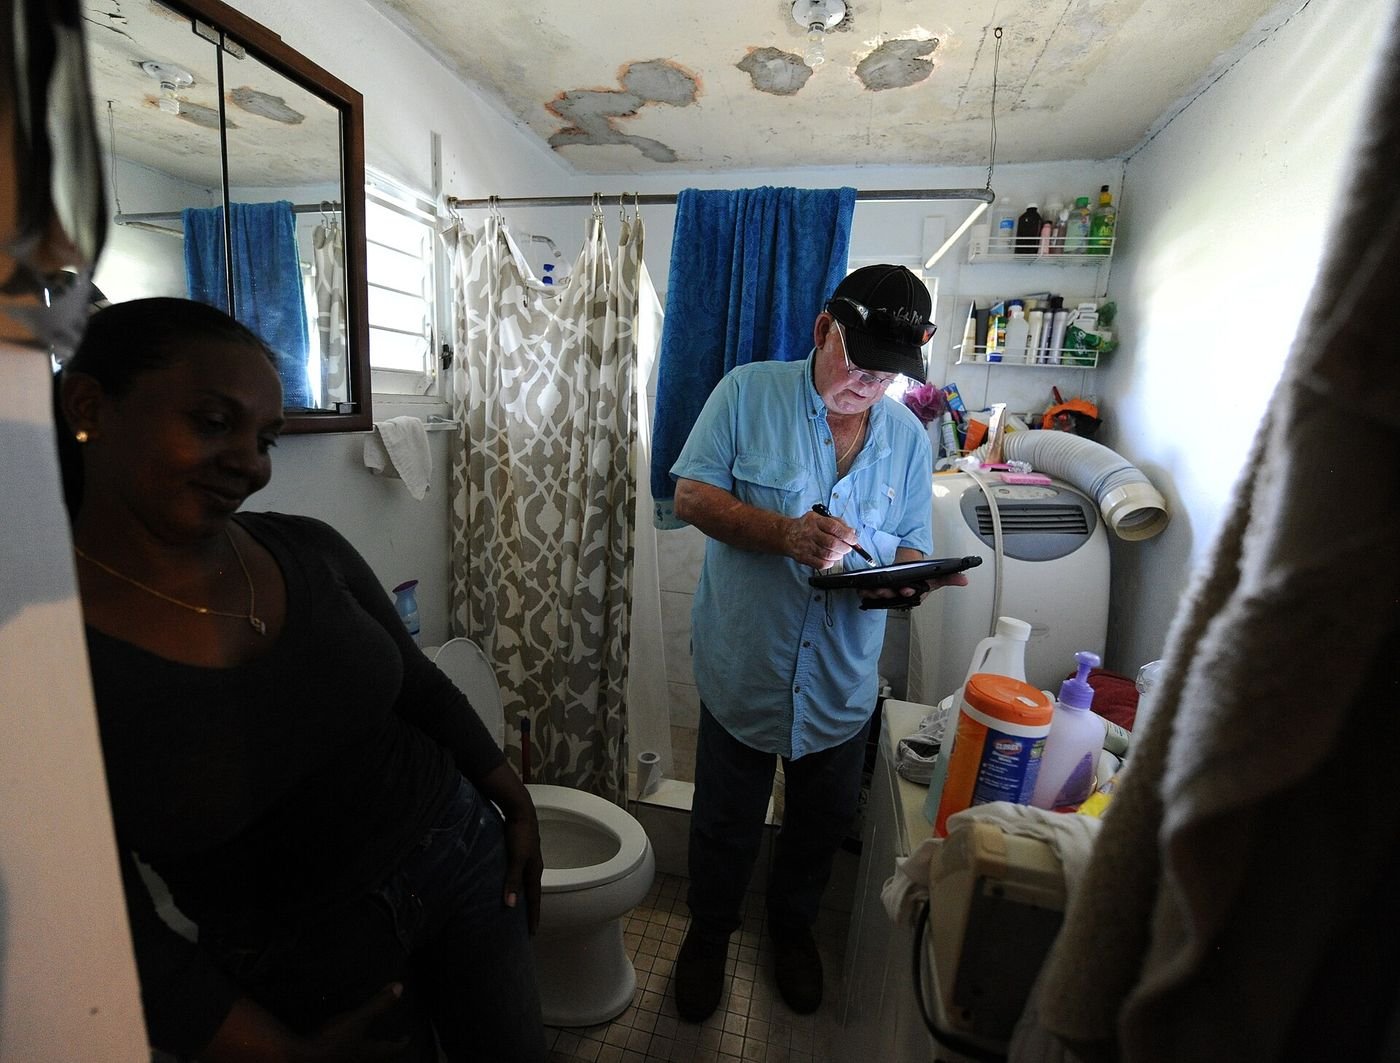
A housing inspector documents water-damaged, peeling ceiling paint in a storm-damaged bathroom
Interior damage · Ceiling water damage is easy to miss in a short visit. U.S. Virgin Islands, 2017 · FEMA / Jocelyn Augustino

2 · “Wind or water? The label decides the payout.”

Lowell brought wind, wind-driven rain, flash flooding, surge and mud at once. Rain through a wind-damaged roof, surge in a ground-floor shop and mud from a hillside can each fall under a different policy — homeowners, hurricane or flood — with different deductibles. A “flood, not covered” letter deserves a second look at the evidence.
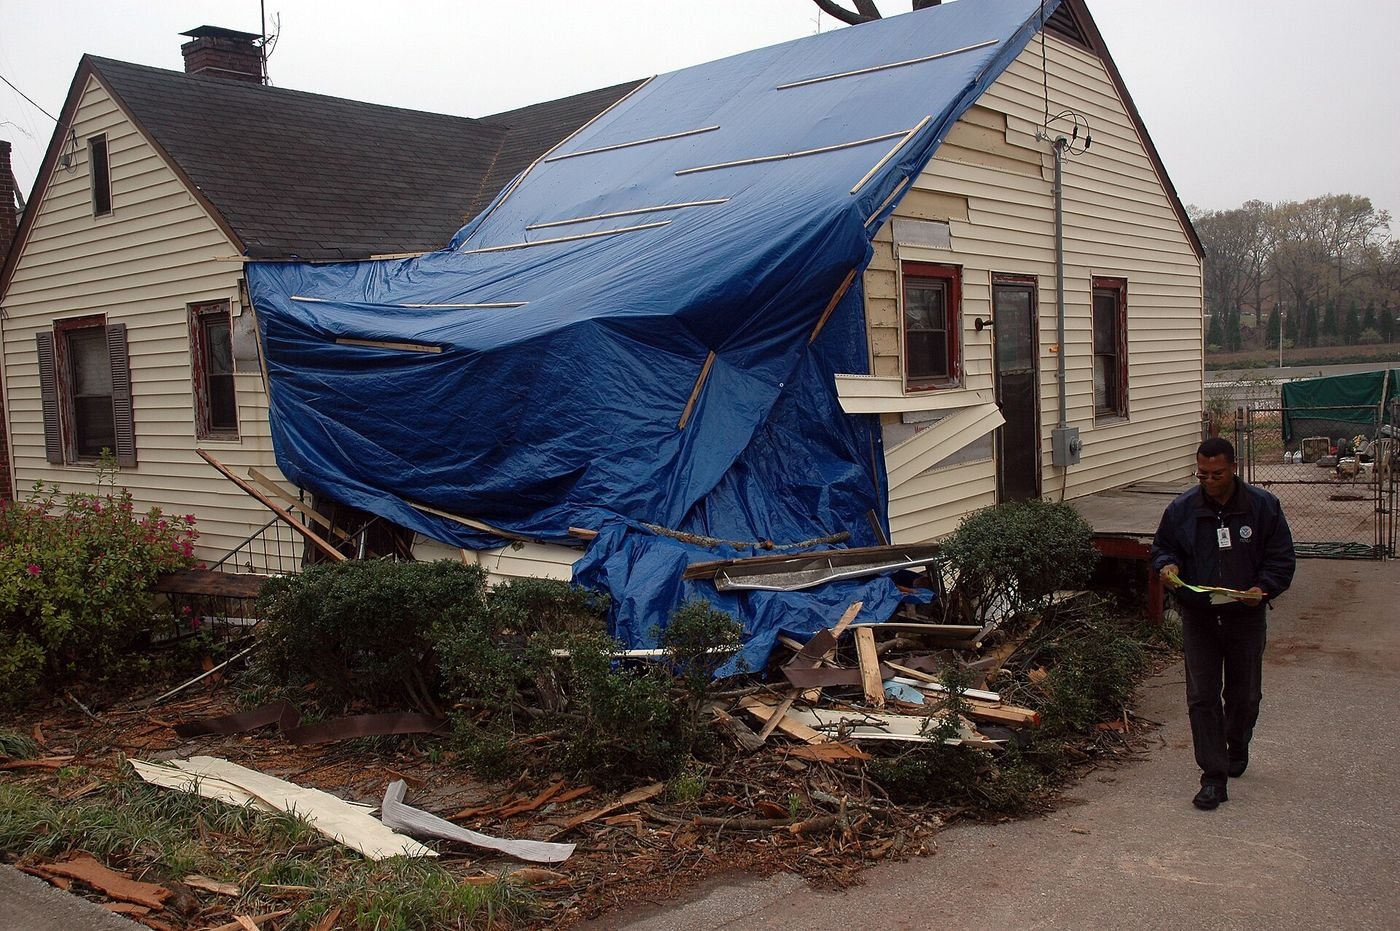
A wind-damaged home with a torn roof and wall covered by a blue tarp, with siding and debris in the yard
Wind or water? · Wind opened this home; rain followed it in. Georgia, 2008 · FEMA / Robert Kaufmann

3 · “Trees, fences and outages add up.”

Fallen trees, debris removal, fences, carports and awnings, spoiled food, a hotel stay while the house dried out, a shop closed for two weeks without power — each can be its own line item under the right coverage. Keep every receipt, closure notice and outage record.
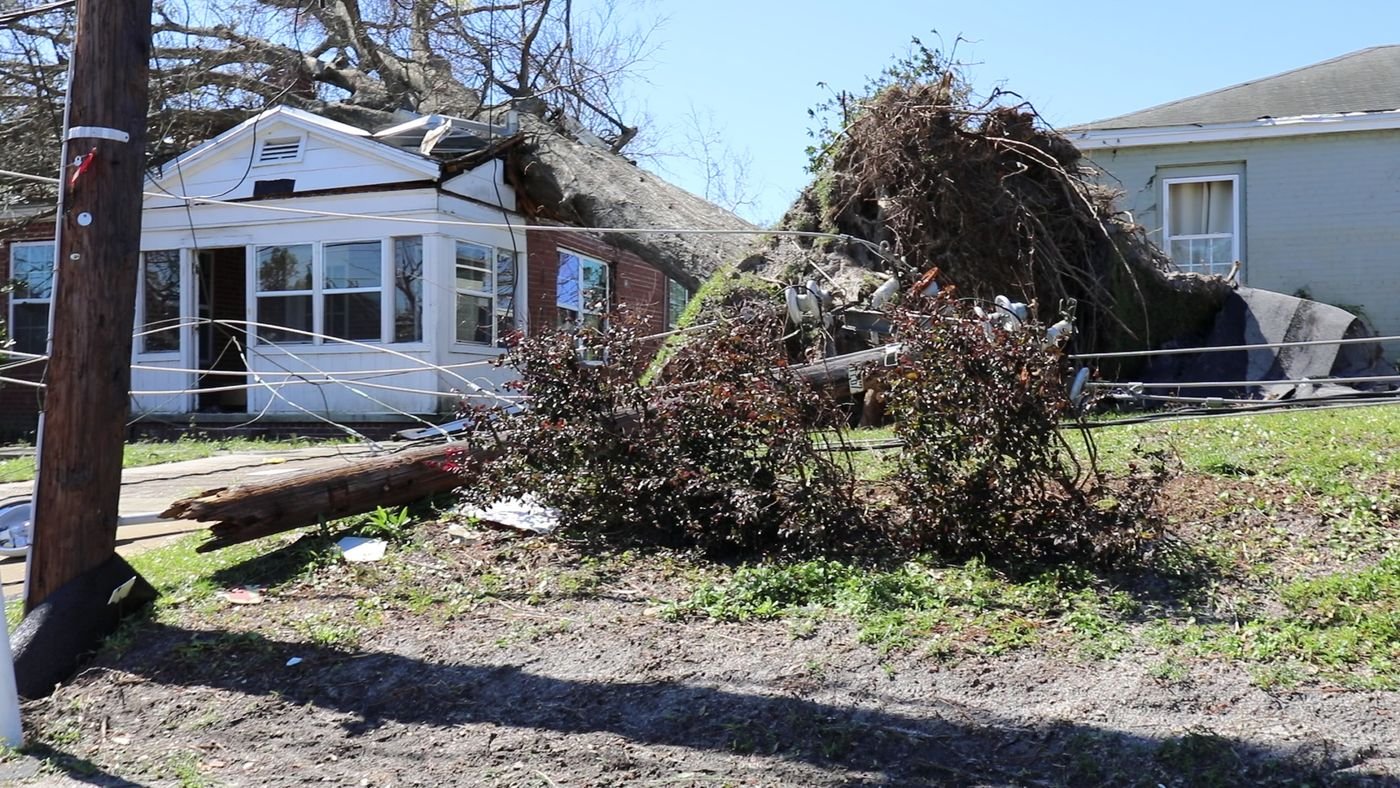
Large trees uprooted by hurricane winds lying on homes and a front yard
Fallen trees · Trees on roofs, fences and lanais are covered losses to scope. Hurricane Michael, Florida, 2018 · VOA / M. Amaya
Why local matters now

Out-of-state public adjusters can’t take Lowell claims.

Hawaiʻi’s Insurance Commissioner let out-of-state insurance-company adjusters work Lala, Lowell and Nolo claims — but specifically excluded nonresident public adjusters (Declaration 2026-4LIC, Sept. 25). Island Claims is a licensed, Hawaiʻi-based firm. Headquartered on Maui, serving Kauaʻi and every island.
What it costs$0 upfront, ever. Your review is Complimentary. If we take your claim, our fee is a percentage of the recovery — stated in writing before any work begins. No recovery, no fee. Hawaii Public Adjuster License #553921.
Every Kind of Lowell Loss

Big or Small, Home or Business — It’s Worth a Look

Lowell didn’t only take whole roofs. It lifted shingles across entire neighborhoods, pushed rain through ceilings, dropped trees on lanais, flooded ground-floor shops and cut power for days. These are the losses we see most — and the ones most often under-scoped.

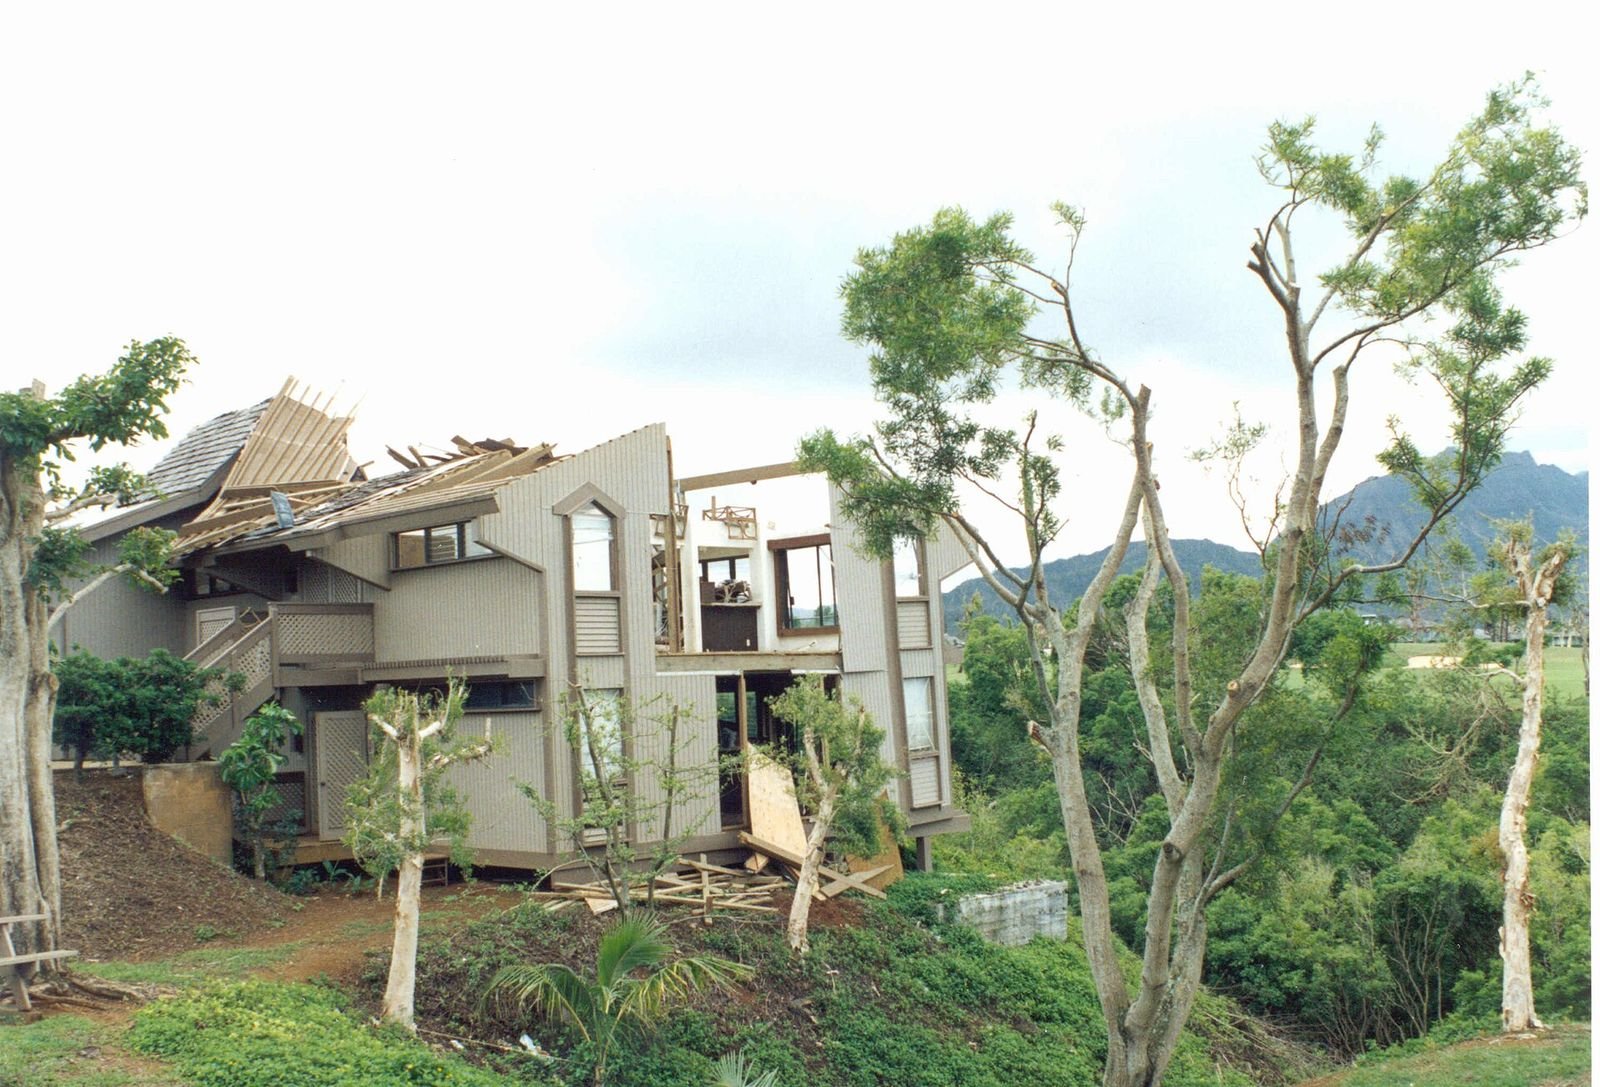
A Kauaʻi home with its roof and upper floor torn open by hurricane winds
Roof & wind damageKauaʻi · Hurricane Iniki, 1992 · FEMA
An inspector documents a water-damaged ceiling inside a home
Ceilings & interior waterU.S. Virgin Islands, 2017 · FEMA
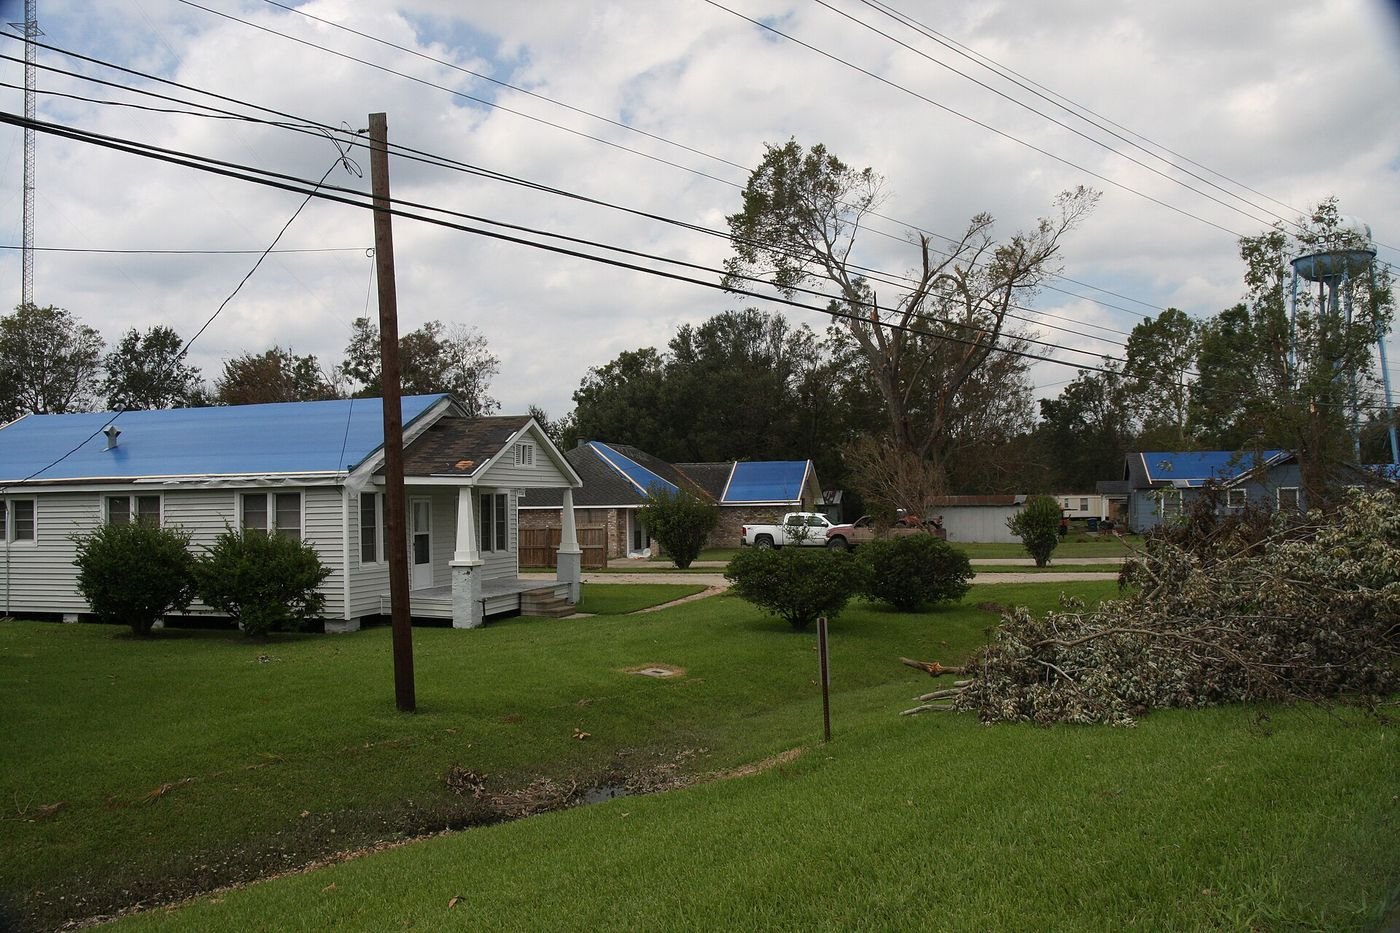
A neighborhood street of homes with blue tarps on damaged roofs and piles of storm debris
Whole-neighborhood shingle lossLouisiana, 2008 · FEMA / Jacinta Quesada
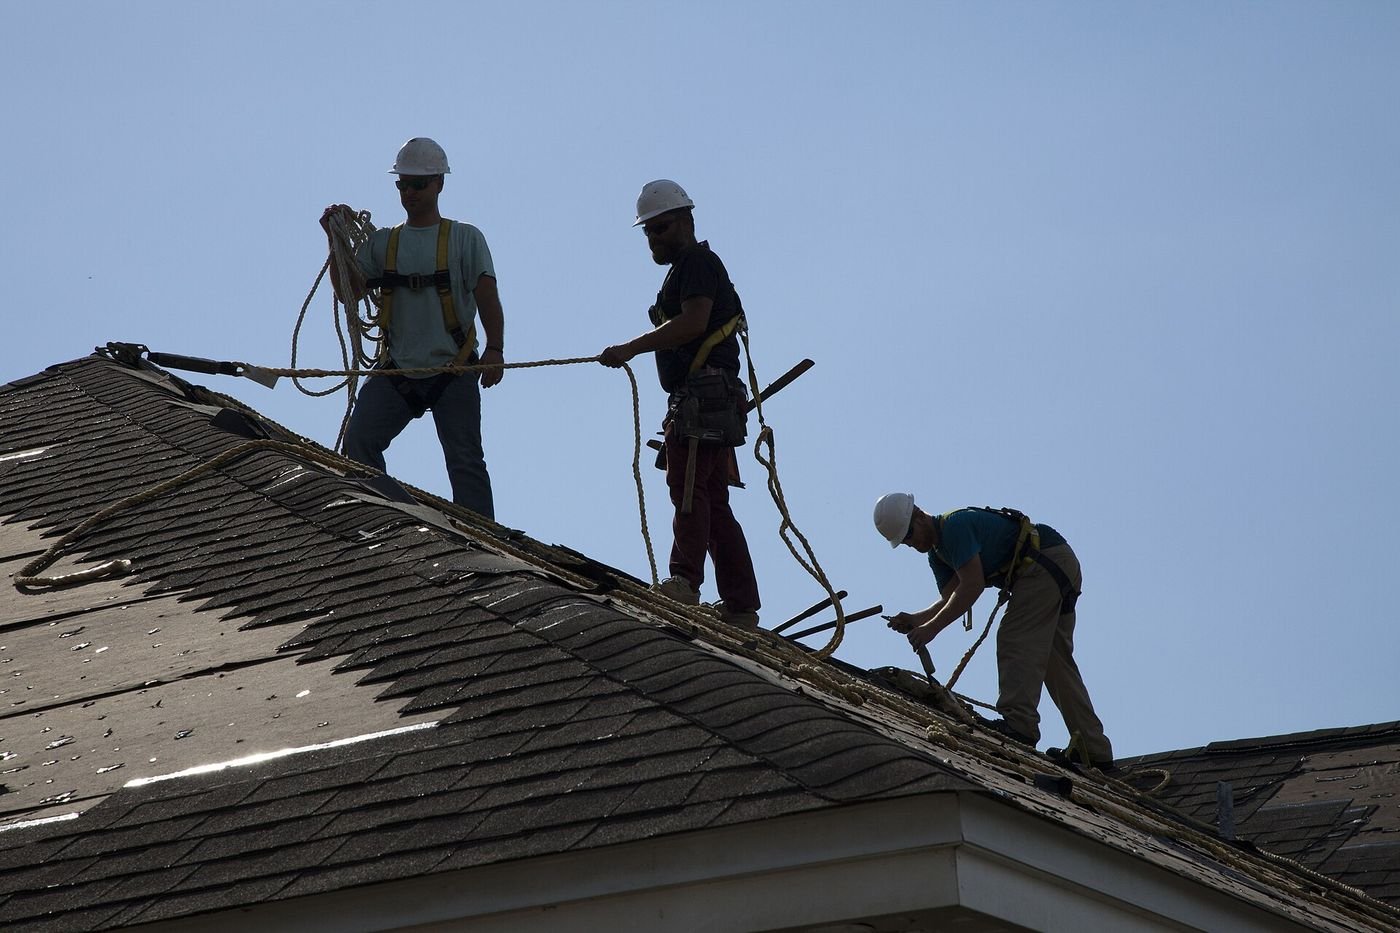
A roofing crew works on a storm-damaged shingle roof
Smaller roof repairsFlorida, 2018 · USACE / Patrick Bray
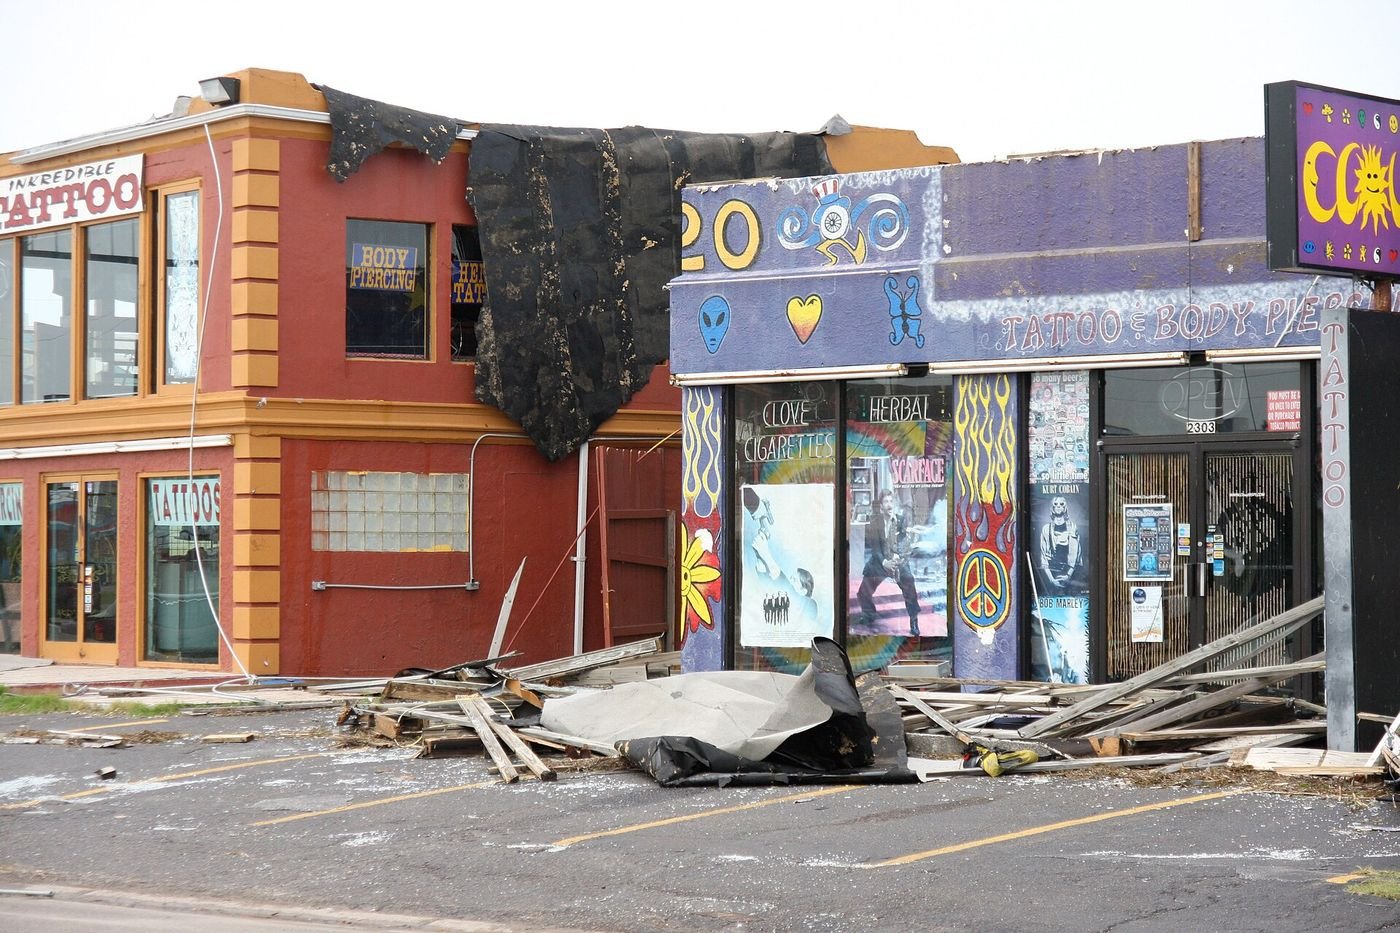
Storefronts with torn roofs and debris in the parking lot after a hurricane
Storefronts & businessesTexas, 2008 · FEMA / Jacinta Quesada
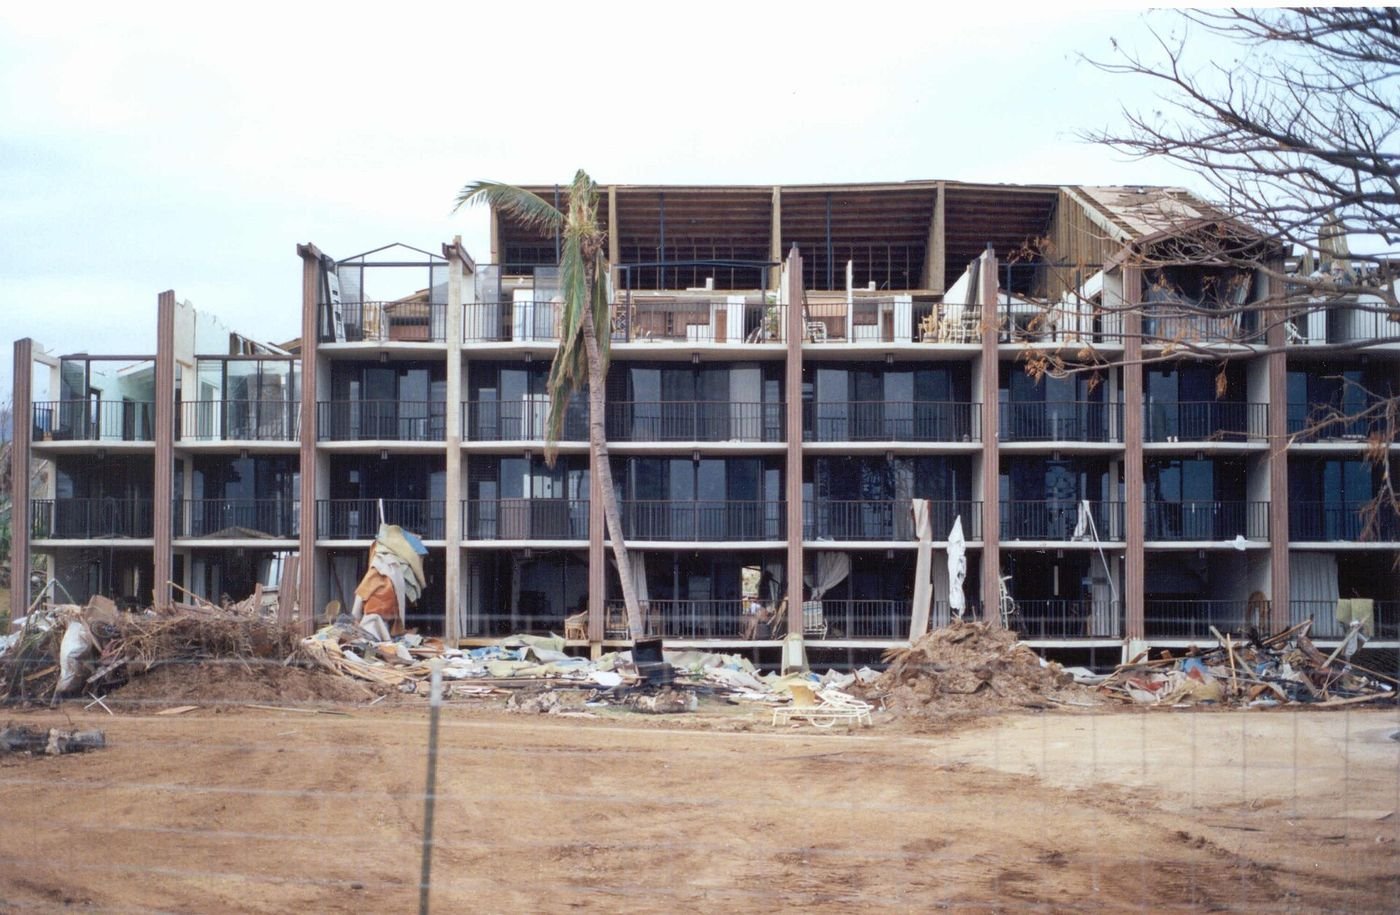
A multi-story Kauaʻi apartment building with its roof blown off
Condos, rentals & AOAOsKauaʻi · Hurricane Iniki, 1992 · FEMA
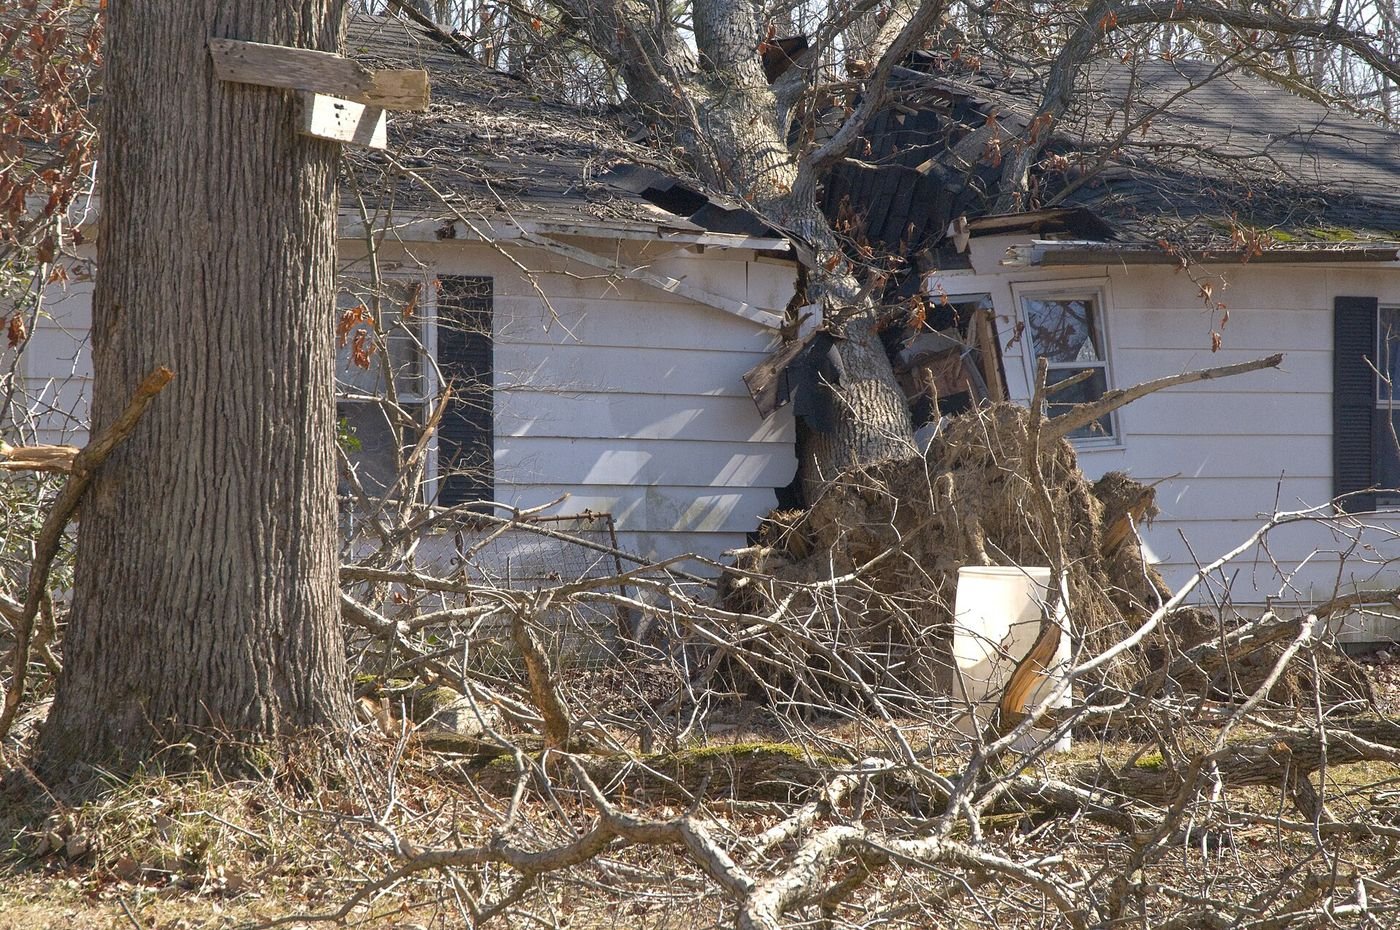
A large tree fallen through the roof and wall of a house
Trees on homes & lanaisKentucky, 2009 · FEMA / Liz Roll
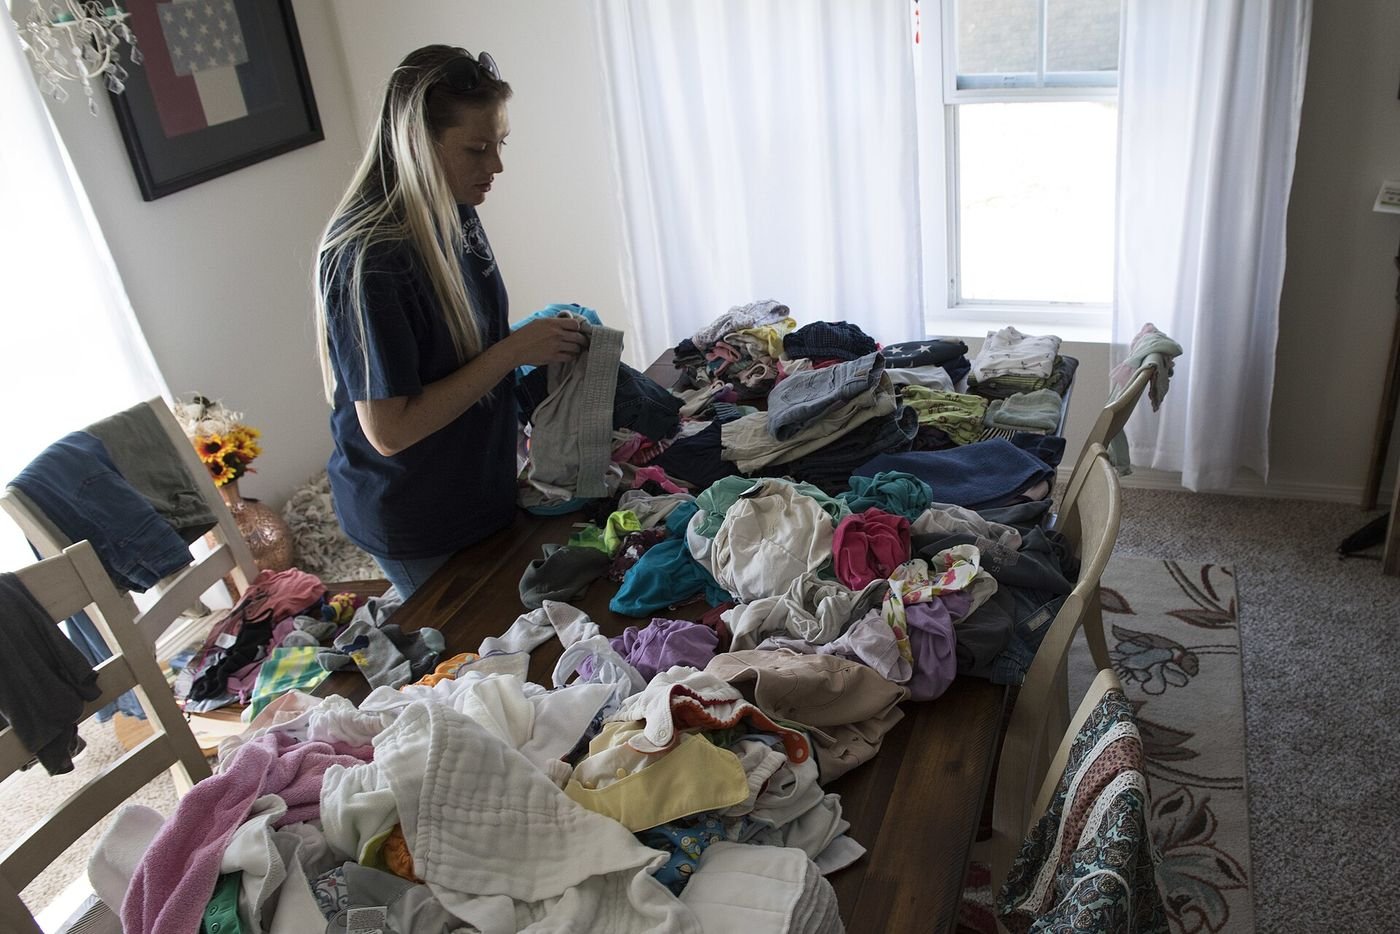
A homeowner sorts through water-damaged clothing and belongings
Contents & belongingsFlorida, 2018 · U.S. Air Force

Photos are from Hurricane Iniki on Kauaʻi and other U.S. storms (FEMA and federal public-domain images) and illustrate common loss types — they are not photos of Lowell-damaged properties.

Dates & Protections

What’s on the Calendar for Lowell Owners

Sept 302026
Kauaʻi property tax exemptions due

The County’s annual real property tax exemption filing deadline is Wednesday, Sept. 30 — no extensions. Separate disaster relief for storm-damaged property can be requested through June 30, 2027. Real Property Assessment: (808) 652-7490.

Sept 25Declaration
Insurance Commissioner Declaration 2026-4LIC

Covers Lala, Lowell and Nolo. Lets nonresident independent (insurer-side) adjusters work claims here temporarily — and keeps nonresident public adjusters out.

Jan 72027
Insurer grace periods requested

Insurance Commissioner Memorandum 2026-8A asks insurers to offer grace periods and payment plans, avoid cancelling or non-renewing for non-payment, and extend inspection deadlines for Lowell policyholders through Jan. 7, 2027. Ask your insurer directly.

PendingFederal
Major Disaster Declaration

Requested Sept. 9 for Kauaʻi and Maui counties. If approved with Individual Assistance, registration opens at disasterassistance.gov or 1-800-621-3362 with its own deadline.

Your policyCheck now
Notice, proof of loss & suit limits

Every policy sets its own time limits for reporting, proof of loss, supplements and disputes. Get yours identified early — we do that in every Complimentary review.

Lowell Claim Questions

Answers Before You Sign Anything

Often, yes. A first payment is frequently based on a quick inspection, and cashing it does not automatically close your claim — many policies allow supplemental claims for damage that was missed or underpriced, within the policy’s time limits. Read every letter for words like “final” or “release,” keep the estimate, and have it compared to the actual damage before you sign anything that settles the claim.
Not necessarily. Lowell brought wind, wind-driven rain, flash flooding, surge and mud at the same time, and the cause of each part of the damage decides which policy responds — homeowners, a separate hurricane policy, or flood. Rain through a wind-created opening is treated very differently from rising surface water. When causes overlap, the evidence (water lines, opening points, timing, debris) matters, and the loss may need to be allocated rather than denied outright.
It may. Lowell prompted a hurricane warning for Kauaʻi and Niʻihau, and many Hawaiʻi policies use a percentage hurricane deductible or a separate hurricane policy that is triggered by specific National Weather Service warnings. The exact trigger wording, which islands it names, and whether the damage falls inside the storm window all matter. We check this in every Complimentary review.
It depends on what the tree hit and on your policy’s debris-removal terms. When a fallen tree damages a covered structure — roof, lanai, fence, carport — removal is often included, usually with a dollar limit. Trees that fall without damaging anything are commonly covered only in narrow situations, if at all. Photograph the tree where it fell before cleanup and keep every removal invoice.
No. Your insurance claim is separate and should move now. Governor Green requested a Major Disaster Declaration for Kauaʻi and Maui counties on September 9; as of September 28 it is still pending. If it is approved with Individual Assistance, FEMA registration opens at disasterassistance.gov — and FEMA does not pay for losses your insurance covers, so the insurance claim comes first. File a County damage report too (kauairecovers.org or dial 211).
Not under the current emergency rules. Hawaiʻi’s Insurance Commissioner allowed out-of-state independent adjusters (who work for insurance companies) to handle Lala, Lowell and Nolo claims, but specifically excluded nonresident public adjusters (Declaration 2026-4LIC, Sept. 25, 2026). Anyone representing you must hold a Hawaiʻi public adjuster license — you can verify it on the NAIC license lookup. Island Claims is a Hawaiʻi-based firm, license #553921.
Official Lowell Help

Free Programs & Updates You Can Use Right Now

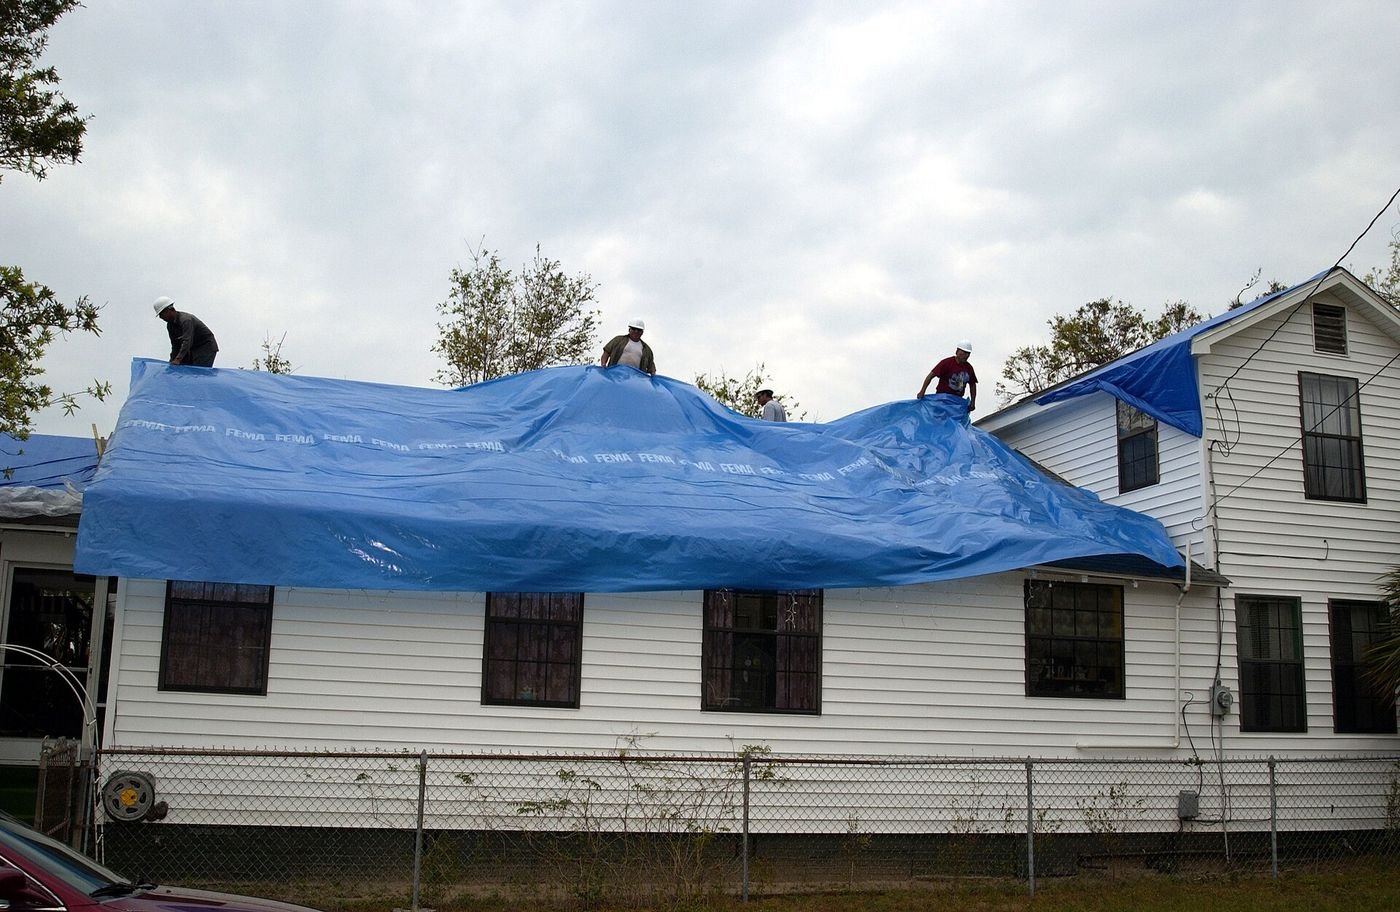
A crew stretches a blue tarp over a storm-damaged roof to stop further water damage
Temporary repairs · Tarping to prevent further damage is usually part of the claim — keep every receipt. Florida, 2004 · FEMA / Bill Koplitz
Kauaʻi recovery hubCounty of Kauaʻi — damage reports, debris, resources · or dial 211
Hurricane Resource CentersHanalei & Kōloa Neighborhood Centers · 9 a.m.–4 p.m. (hours may change)
Insurance claim questions & complaintsHawaii Insurance Division — state regulator, free help for policyholders
Kauaʻi Emergency ManagementKEMA — alerts: text KAUAIEMA to 888777
Electric bill helpKIUC member services & payment assistance
Replacement SNAP for food lost in outagesState Department of Human Services
Emotional support, 24/7Free, confidential · disaster distress line 1-800-985-5990

These programs are free and separate from your insurance claim — use them. None of them replaces what your policy may owe you for your property.

Helpful Resources

Whether You Hire Us or Not